On October 12, 2026, a South Korean bank quietly rewrote the rulebook for corporate finance. Jeonbuk Bank launched the country's first regulated Bitcoin-backed won loan program, explicitly allowing businesses to fund operating expenses—including crypto payroll obligations—with borrowed fiat secured by BTC holdings (CryptoRank, October 12, 2026). For the first time, a licensed commercial bank is treating cryptocurrency as collateral for general-purpose business lending.
This is not another crypto lending platform. It is a bank supervised by South Korea's Financial Services Commission, issuing loans in local currency against Bitcoin. The development directly reshapes crypto payroll compliance 2026 because it bridges the persistent gap between holding crypto and paying real-world obligations.
Table of Contents
- What Just Happened: Jeonbuk Bank BTC Collateral for Business Lending
- Why a Bitcoin-Backed Business Loan Matters for Crypto Payroll
- Crypto Payroll in Late 2026
- 3 Treasury Decisions Every Crypto Payroll Operator Must Revisit
- What This Signals for Crypto Payroll Platforms
- Recommended Actions This Month
- What to Watch Next
- Common Questions on Crypto Payroll in 2026
- Bottom Line
- Key Takeaways
What Just Happened: Jeonbuk Bank BTC Collateral for Business Lending
Jeonbuk Bank's facility permits South Korean companies to pledge Bitcoin as collateral and receive won-denominated loans. The program went live on October 12, 2026, and explicitly includes payroll among permitted uses. This is the first regulated Jeonbuk Bank BTC collateral facility in South Korea—a jurisdiction that previously confined crypto lending to non-bank platforms.
Unlike crypto-native lending platforms that typically disburse stablecoins, Jeonbuk Bank disburses fiat. That detail is decisive for companies wanting to pay employees in crypto or fund stablecoin payroll without selling their treasury. A business can hold Bitcoin, borrow won against it, and run payroll on Friday without triggering a taxable sale.
Why a Bitcoin-Backed Business Loan Matters for Crypto Payroll
A Bitcoin-backed business loan creates a liquidity bridge: the company borrows fiat against BTC, meets payroll, repays principal plus interest, and retains its original BTC position. The core tension in crypto payroll is that employees and tax agencies expect fiat, while many Web3 treasuries are heavy in volatile assets.
Selling Bitcoin to fund payroll generates a capital gains event. Borrowing does not. For a company sitting on an 80% unrealized gain, the tax impact of a single sale can be substantial. A loan converts that potential tax payment into a deductible interest expense. The decision rule: if the after-tax cost of collateralized borrowing is lower than forgone appreciation plus immediate tax liability, borrowing wins.
When a licensed bank accepts Bitcoin as collateral for payroll-funding loans, it signals that crypto is viable as a treasury asset class. This reshapes conversations with auditors, tax advisors, and compensation committees about DAO payroll crypto arrangements and stablecoin salary programs.
Crypto Payroll in Late 2026
Crypto payroll is no longer fringe, but not yet mainstream for W-2 employees. Contractors in Web3 frequently receive compensation in stablecoins (USDC and USDT dominate) or, more rarely, BTC or ETH. Full-time employees remain mostly paid in fiat because payroll tax withholding and labor law compliance favor national currencies.
The compliance picture: in jurisdictions allowing wage payments in crypto, employers must calculate fair market value at the moment of payment, report it on Form W-2 or 1099, and ensure income tax and FICA are satisfied in fiat. Most businesses avoid direct BTC payroll because volatility means the value received can change between declaration and settlement. That's why any crypto payroll provider comparison today shows stablecoin-based solutions dominating.
For a current crypto payroll provider comparison, Eco's Best Crypto Payroll Platforms 2026: Compared catalogues providers across three tiers: pure crypto payroll apps, traditional payroll services with crypto withdrawal features, and neo-banking platforms that unify fiat accounts, corporate cards, and on-chain asset management. Platforms like OneSafe crypto payroll fall into this third tier, combining multi-currency fiat accounts with crypto custody—the architecture that becomes essential once bank-collateral-backed payroll liquidity enters the picture.
3 Treasury Decisions Every Crypto Payroll Operator Must Revisit
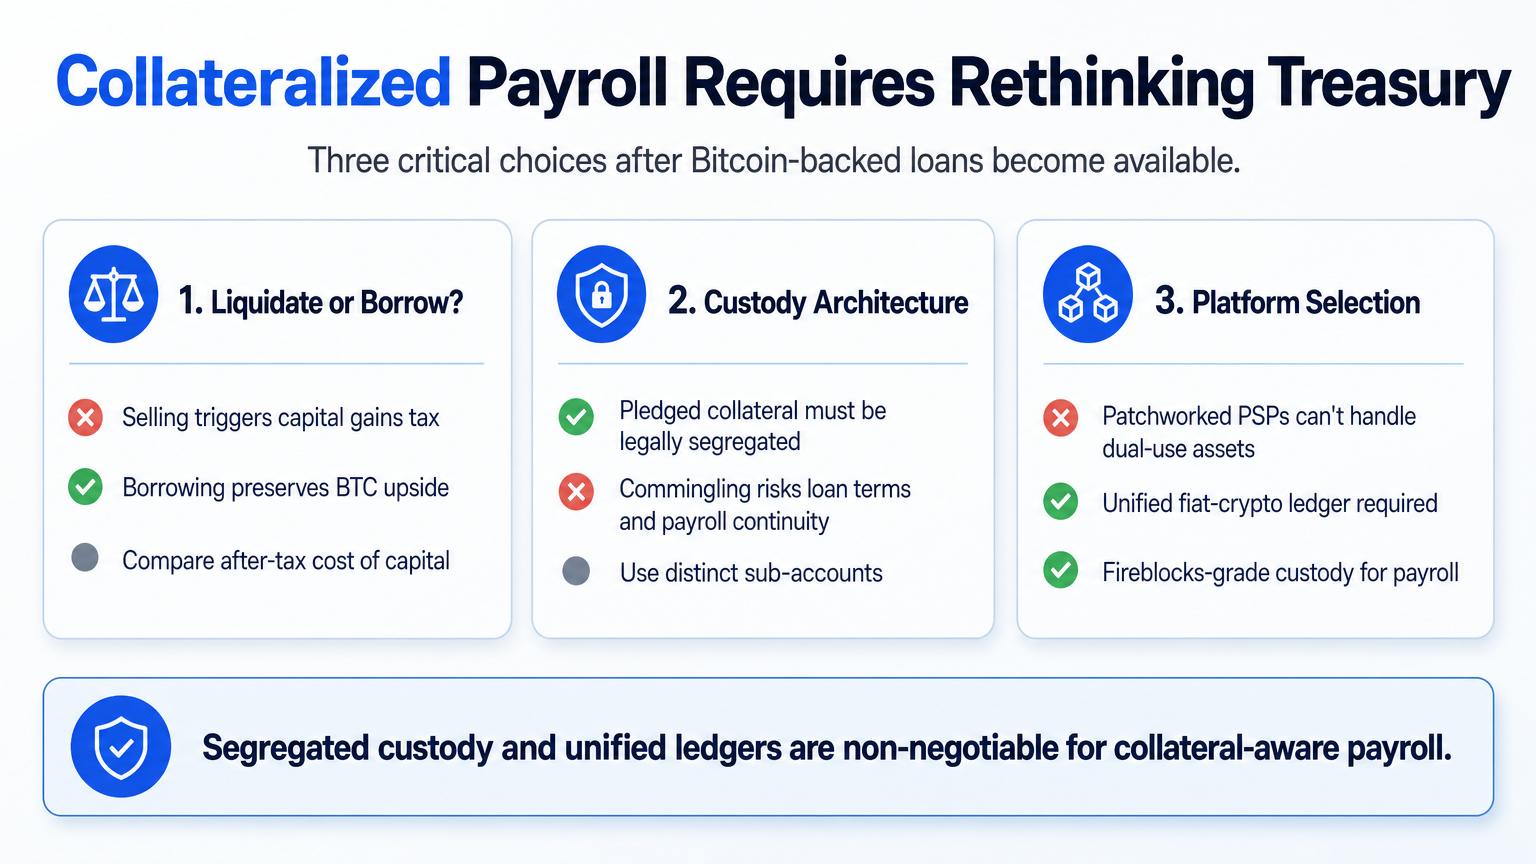
| Decision | Key Trade-off | Infrastructure Required |
|---|---|---|
| Liquidate vs. borrow vs. both | Tax event vs. interest cost; opportunity cost of lost BTC exposure | Real-time cost-of-capital model with bank loan pricing |
| Custody architecture for dual-use assets | Liquidity isolation vs. capital efficiency | Segregated sub-accounts or legal entity separation |
| Platform selection for collateral-aware payroll | Payment-rail simplicity vs. treasury-integration depth | Unified fiat-crypto ledger with Fireblocks-grade custody |
Decision 1 — Liquidate, borrow, or both
Before October 12, a treasurer with a heavy BTC position had a binary choice: sell (crystallize tax) or hold and fund payroll from operating cash. Now the math has a third variable. Companies can compare the effective tax rate on unrealized gains, the interest rate on a Jeonbuk-style loan plus custody fees, and the opportunity benefit of retaining BTC exposure.
Decision 2 — Custody architecture
Once Bitcoin serves as collateral for a payroll-funding loan, the same assets become dual-purpose. If BTC is commingled with operational funds, a margin call or custody breach could threaten both loan terms and payroll continuity. Best practice: hold pledged collateral in a legally distinct account separate from the working capital pool.
Decision 3 — Platform selection
Most payment service providers offering crypto payroll do not integrate bank-grade custody settlement, real-time FX, and direct fiat account access. When a treasury manages loan proceeds, fiat payroll runs, and BTC collateral positions simultaneously, a patchworked PSP setup becomes untenable. The finance team needs a unified ledger. Our guide on Neobank Crypto: A Definitive Guide for Businesses details what this requires under the hood.
What This Signals for Crypto Payroll Platforms
The Jeonbuk Bank loan changes the treasury layer that funds payrolls. For platforms competing in the space, competence in asset custody, segregation, and fiat-crypto interoperability now outweighs payroll UX. A OneSafe crypto payroll approach—global accounts, instant crypto-to-fiat conversion, Fireblocks-secured custody—reflects the minimum viable architecture for companies that might pledge BTC for a payroll loan and route fiat to employees across jurisdictions.
Payroll has always required separation of duties. In a crypto treasury, that extends to asset pools. Platform-native customizable roles down to sub-account levels make it possible to keep pledged BTC in one custody account, stablecoin payroll reserves in another, and fiat operating cash in a third with distinct authorization paths. Once a commercial bank holds a claim on your collateral, commingling becomes a liability.
Recommended Actions This Month

- Audit your crypto payroll treasury for dual-use exposure. Map every asset pool earmarked for both collateral and salary funding. If a single wallet holds both purposes, prioritize separation.
- Test a regulated crypto-collateral loan scenario in your cost model. Build a spreadsheet comparing selling BTC (with tax impact), borrowing BTC-backed fiat, and doing nothing. Use actual payroll volume and last quarter's tax effect.
- Evaluate whether your payroll provider segregates crypto assets from operational funds. Ask for a written description of sub-account structure. If the answer is "everything is one omnibus wallet," treat that as a deficiency requiring a compensating control or platform migration.
- Watch Korea's FSC policy updates for guidance on third-party custody, reporting requirements, and cross-border recognition of collateral arrangements. Subscribe to the CryptoRank feed.
What to Watch Next
- Collateral eligibility expansion: ETH and top-tier stablecoins will likely follow BTC, further normalizing the loan-to-payroll path.
- Regulatory reciprocity: Will a South Korean KYC/AML standard for crypto collateral be recognized by US or EU regulators when the borrower operates cross-border? This determines whether a Bitcoin-backed payroll loan obtained in Korea can fund a subsidiary's payroll elsewhere.
- Labor board treatment: If payroll funds come from a fiat loan secured by crypto, the wage itself is fiat. Does that remove ambiguity about wage-and-hour law applicability? Expect a test case within 12–18 months.
- Payroll-specific proof-of-reserves: If a company uses the same BTC as collateral and a reserve backing future salary commitments, employees may begin asking for attestations that the collateral is unencumbered for the portion allocated to salaries.
Common Questions on Crypto Payroll in 2026
Is it legal to pay wages in crypto?
Yes, in a growing number of jurisdictions, provided all employment taxes are properly withheld and remitted in local fiat. The US Fair Labor Standards Act does not prohibit paying wages in digital assets, but requires wages be paid "in cash or negotiable instruments payable at par." Several states interpret stablecoins and convertible crypto as meeting that standard when the employer withholds and pays payroll taxes in USD. The PayrollOrg Cryptocurrency hot topics page regularly updates jurisdictional guidance.
How is crypto payroll taxed?
Crypto received as compensation is treated as ordinary income at fair market value on the date of receipt. The employer must report that value on standard payroll forms and withhold income tax and mandatory contributions, remitted in fiat. When the employee later sells or spends that crypto, a secondary capital gains event may occur. The critical point: valuing crypto at the exact moment of payment using a consistent, auditable source. Errors trigger penalties.
Is crypto payroll safe?
Safety has two dimensions: custody security and regulatory protection. Funds held with a qualified custodian enjoy stronger technical safeguards than assets on consumer exchanges. From a regulatory standpoint, payroll funds deposited with a licensed banking partner benefit from standard commercial safeguards. The safety gap appears when companies use unregulated non-custodial wallets without role-based access controls.
Who uses crypto payroll in 2026?
Adoption is concentrated among three profiles: (1) Web3-native startups and DAOs that hold treasury in digital assets and employ globally distributed contractor-heavy teams—this is where DAO payroll crypto is standard practice; (2) cross-border service firms in regions with slow banking corridors where stablecoin payroll offers faster settlement; and (3) a small cohort of mid-sized tech companies experimenting with partial crypto salary options as a recruitment tool.
Bottom Line
A Korean commercial bank treating Bitcoin as collateral for payroll-funding loans validates a treasury model companies have been working toward informally: hold crypto, borrow fiat, pay employees, keep the upside. As of October 13, 2026, any finance leader managing a crypto treasury must treat payroll not as a liquidation-dependent activity but as a cash-flow management exercise with multiple funding paths.
For global businesses seeking to bridge crypto holdings and real-world payroll obligations, OneSafe provides the unified neo-banking foundation required to execute these strategies securely, with segregated accounts, instant fiat-crypto conversion, and KYB-compliant onboarding typically completed in under a week.
Key Takeaways
- Jeonbuk Bank's Bitcoin-backed won loan, launched October 12, 2026, is the first regulated bank product that explicitly lets businesses use BTC collateral to fund payroll, making crypto payroll compliance 2026 a bank-underwritten reality.
- The loan creates an alternative to selling BTC for payroll liquidity—avoiding immediate capital gains taxes and preserving upside exposure, turning cost-of-capital analysis into a concrete exercise.
- Crypto payroll operators must now treat asset segregation as mandatory because the same Bitcoin can simultaneously serve as collateral and backstop for salary commitments.
- Platform selection should prioritize unified fiat-crypto ledgers with institutional-grade custody, because patchworked PSP setups cannot handle collateral-aware payroll reconciliation.
- The Jeonbuk event will accelerate regulatory reciprocity conversations in ASEAN, the US, and the EU, making a cross-border crypto-collateral payroll corridor likely before the end of 2027.