Table of Contents
- What Just Happened: Ripple’s App Play for Stablecoin Payments
- Why This Matters: Stablecoin Payments Break Out of the Backend
- Stablecoin Payments 101: A Quick Primer for Operators
- What This Means for Your Business Today
- Open Questions and What to Watch Next
- Key Takeaways
What Just Happened: Ripple’s App Play for Stablecoin Payments
The Ripple Privy Integration
On October 13, 2026, Ripple announced a partnership with Privy—the embedded wallet provider Stripe acquired—to bring XRP and RLUSD stablecoin payments directly into consumer applications through the XRP Ledger. The deal, reported by Crypto News on October 13, gives developers tools to embed programmable wallets inside their apps, handle wallet creation and transaction signing through software, and support both user-facing payments and autonomous AI agent transactions.
Privy’s infrastructure will allow apps to offer stablecoin payment functionality without requiring end users to manage private keys themselves—a friction point that has historically kept cryptocurrency payments confined to exchanges and dedicated wallets. The Ripple Privy integration supports XRP, Ripple’s dollar-backed RLUSD stablecoin, and other assets issued on the XRP Ledger.
AI Agents Already Moving Money: 13 Million Transactions
The announcement included a striking data point. According to Ripple, AI agents have already executed 13 million payments on the XRP Ledger, and agent-driven transactions now account for roughly 25% of all network activity. These are not simulated testnet transactions; they are live, on-chain payments initiated by non-human actors.
Privy explicitly framed the XRPL integration as enabling “agentic commerce”—applications where AI agents can autonomously spend, receive, and programmatically manage funds. This is a concrete, dated development (October 13, 2026) that extends stablecoin utility beyond what most businesses currently model in their payment strategies.
Why This Matters: Stablecoin Payments Break Out of the Backend
From Settlement Layer to Consumer App
For years, stablecoin payments have functioned primarily as settlement infrastructure. Circle’s USDC, Tether’s USDT, and similar assets settled transactions faster and cheaper than correspondent banking, but the experience for end users remained largely invisible—APIs moving value in the background while fiat-denominated interfaces sat on top.
The Ripple-Privy partnership changes the architecture. By embedding wallets directly into applications, the stablecoin becomes the user-facing payment method, not just the settlement rail. A consumer inside a fintech app, a marketplace, or a gaming platform can hold and spend RLUSD or XRP payments without leaving the experience or managing seed phrases.
This matters because distribution is the bottleneck for any stablecoin adoption business case. The technology works; the missing piece has been consumer accessibility. When wallet providers like Privy—backed by Stripe’s distribution reach—embed stablecoin functionality into the application layer, they reduce the adoption barrier to near zero. A generation of stablecoin payment apps is emerging where the wallet is invisible and the payment just works.
The New World of Programmable, Agent-Driven Payments
The 13-million-agent-transaction figure is not a curiosity. It represents a category of payment volume that most treasury and finance teams have not planned for: programmatic payments executed by non-human actors.
Consider a practical scenario. A DAO treasury management bot rebalances stablecoin holdings across protocols based on yield conditions. An AI procurement agent pays a freelance developer in USDC once a GitHub pull request is merged and verified. A supply chain smart contract releases payment to a logistics provider when an IoT sensor confirms delivery. These are the types of AI agent payments stablecoin rails now support at scale, and they account for a quarter of XRPL activity.
For businesses, this introduces a new operational question: is your payment infrastructure capable of both initiating and receiving autonomous stablecoin payments? If an AI agent your company deploys can spend programmatically, you need custody controls, spending limits, and audit trails built for non-human actors. If your business receives agent-initiated payments, your reconciliation workflows must handle transactions that arrive at any hour, from wallet addresses not tied to a human counterparty.
The Stablecoin Payments: Distribution Battle Heats Up analysis earlier this year anticipated this shift toward front-end integration, but the Ripple-Privy deal and the agent payment data give it a concrete, dated anchor.
Stablecoin Payments 101: A Quick Primer for Operators

What Are Stablecoin Payments and Why Do They Matter?
Stablecoins are cryptocurrencies designed to maintain a stable value relative to a reference asset, typically the US dollar. USDC, USDT, and RLUSD are prominent examples. When a business sends or receives a stablecoin, it settles on a blockchain—usually within seconds to minutes—without passing through correspondent banking networks.
Stablecoin payments matter for three practical reasons: speed (near-instant settlement versus 2-5 days for international wires), cost (fractions of a cent to a few dollars regardless of amount, versus $25-50 for SWIFT transfers), and programmability (smart contracts can automate payment conditions that require manual intervention in the fiat world).
The Established Players: Stripe, Circle, and Visa’s Solutions
The ecosystem has matured rapidly. Circle provides USDC issuance and infrastructure. Stripe has built stablecoin payout capabilities and, through the Privy acquisition, embedded wallet infrastructure. Visa has piloted USDC settlement on Ethereum and expanded its stablecoin settlement capabilities through 2025 and 2026. A comprehensive list of 77 stablecoin payment platforms now exists, and the best stablecoin payment providers in 2026 now offer custody, compliance, and fiat integration alongside raw on-chain settlement.
Regulatory infrastructure is catching up. The GENIUS Act in the US and MiCA in Europe are defining compliant frameworks for stablecoin issuance and usage, moving the asset class from regulatory gray zone toward supervised financial infrastructure.
What This Means for Your Business Today
AI Agents and Autonomous Payments: Opportunity or Challenge?
The Ripple announcement forces a practical conversation: if AI agents are already executing millions of payments on production networks, where does your business fit?
Opportunity side: businesses that deploy payment agents can automate treasury operations, vendor payments, and revenue collection with latency measured in blocks, not banking days. Programmable money for startups means a global contractor network can be paid in USDC upon work verification without running manual payment runs.
Challenge side: receiving agent-initiated payments introduces compliance, reconciliation, and custody questions. Does your crypto treasury management process distinguish between human-initiated and agent-initiated inflows? Can your accounting systems ingest transactions that arrive continuously rather than in batched settlements? If an agent misbehaves—spending due to a faulty oracle or prompt injection—do you have controls in place?
Integrating Stablecoin Payments: Build, Partner, or Use a Platform
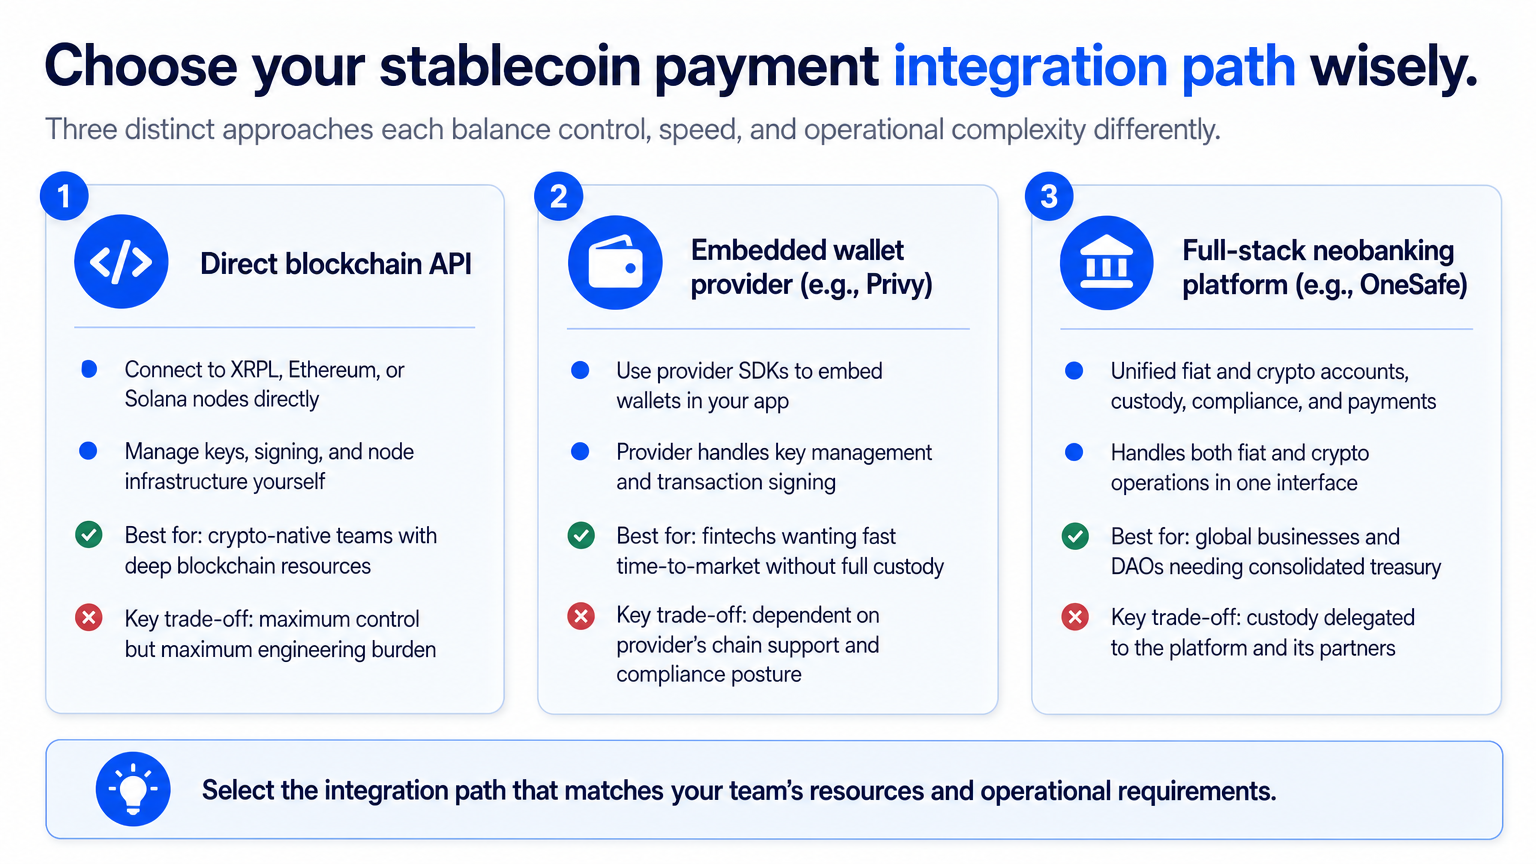
Businesses now face three distinct integration paths for stablecoin payments, each with different trade-offs. The Ripple-Privy deal adds a new option to an already complex stablecoin payment strategy.
| Integration Path | How It Works | Best For | Key Trade-off |
|---|---|---|---|
| Direct blockchain API | Connect to XRPL, Ethereum, or Solana nodes; manage keys, signing, and node infrastructure yourself | Crypto-native teams with deep blockchain engineering resources | Maximum control; maximum engineering and security burden |
| Embedded wallet provider (e.g., Privy) | Use provider SDKs to embed wallets in your app; provider handles key management, transaction signing | Fintechs and apps wanting to offer stablecoin payments without full custody infrastructure | Faster time-to-market; dependent on provider's chain support and compliance posture |
| Full-stack neobanking platform (e.g., OneSafe) | Unified platform handling fiat and crypto accounts, custody, compliance, and payment workflows | Global businesses and DAOs needing both fiat and crypto operations in one interface | Broader functionality; custody is delegated to the platform and its partners |
The embedded wallet approach that Ripple and Privy are advancing sits in the middle. It solves the technical integration challenge—developers call an SDK, not a blockchain node—but it does not solve the operational workflow challenge. A business still needs to reconcile stablecoin payments with fiat treasury, manage multi-currency accounting, handle FX conversion, and maintain compliance across jurisdictions.
This is where a unified fiat-crypto operating system becomes relevant. If your business receives stablecoin payments but pays suppliers in fiat, or holds treasury in both USDC and USD, a fragmented stack (wallet provider plus traditional bank plus FX provider) introduces latency, reconciliation errors, and additional counterparty risk.
The Case for a Unified Fiat-Crypto Operating System
A business receiving stablecoin payments from customers or agents typically needs to: custody those assets securely, convert to fiat when necessary, pay vendors and contractors in multiple currencies, issue spend-controlled cards for team expenses, and maintain audit-ready records across both asset classes.
Doing this with separate services—a crypto wallet here, a business bank account there, a third-party FX provider—creates a reconciliation burden that scales poorly. A platform that natively handles both fiat and crypto, like OneSafe, collapses these functions: stablecoin deposits arrive in the same interface as wire transfers, crypto-fiat payments execute at competitive rates, and corporate cards pull from unified balances.
For DAOs specifically, the combination of secure custody via Fireblocks and customizable role-based permissions addresses a critical gap: treasury management where multiple signers with different authority levels can approve stablecoin payments while maintaining on-chain transparency.
Open Questions and What to Watch Next
What just happened with Ripple and Privy, and how does it affect stablecoin payments?
On October 13, 2026, Ripple and Stripe-owned Privy announced a partnership to bring embedded XRP Ledger wallets into consumer applications. Developers can now build stablecoin payment functionality—including support for RLUSD and XRP—directly into their apps through Privy’s SDK, without requiring users to manage private keys. This shifts stablecoin payments from backend settlement infrastructure to consumer-facing payment features, and it validates embedded wallets as the distribution mechanism for mainstream stablecoin adoption.
How are stablecoin payments moving from backend settlement to consumer-facing apps?
The architectural shift is from API-mediated settlement (where stablecoins move value in the background while users see fiat balances) to embedded wallet experiences (where users hold and spend stablecoins directly within apps). The Privy infrastructure handles wallet generation, key management, and transaction signing invisibly. This makes stablecoin payments feel like any other app-native payment method, which removes the UX barrier that has limited everyday stablecoin usage.
What are the implications of AI agents executing cryptocurrency transactions automatically?
Agent-driven payments create operational demands that most businesses have not addressed: custody controls for non-human spenders, reconciliation workflows for continuous transaction streams, and compliance processes for counterparties that are smart contracts rather than identified entities. The 13-million-agent-transaction milestone on XRPL (October 2026) signals that autonomous payments are production-scale now, not experimental. Businesses need payment infrastructure that can both execute and receive agent-initiated stablecoin transactions with appropriate controls.
How can a global business or startup integrate stablecoin payments into its operations?
Three paths exist: direct blockchain integration (maximum control, maximum engineering burden), embedded wallet providers like Privy (faster launch, depends on provider infrastructure), and full-stack platforms that combine fiat and crypto operations. The right choice depends on whether the business needs only payment acceptance or a complete crypto banking and treasury workflow. Most global businesses will need stablecoin custody, fiat conversion, multi-currency accounts, and compliance support—functionality that exceeds what an embedded wallet alone provides.
What are the security and regulatory risks of holding and transacting in stablecoins?
Security risks include private key compromise, smart contract vulnerabilities, and custody provider failure. Regulatory risks vary by jurisdiction: MiCA imposes specific requirements on stablecoin issuers in Europe, while US frameworks remain fragmented though evolving with legislation like the GENIUS Act. Businesses must evaluate whether their stablecoin custody solution uses institutional-grade security (such as Fireblocks MPC-based custody), enforces multi-factor authentication, and maintains compliance with relevant licensing regimes. A platform that delegates custody to regulated partners and enforces DeFi compliance standards reduces, but does not eliminate, these risks.
Why would a business choose a unified fiat-crypto platform over multiple separate services?
Operational efficiency and reduced counterparty risk. A fragmented stack (traditional bank + crypto wallet + FX provider + corporate card issuer) creates multiple reconciliation points, increases latency on cross-asset payments, and complicates audit trails. A unified platform provides single-interface visibility across fiat and stablecoin balances, instant crypto-to-fiat conversion without moving funds between providers, consistent compliance and security standards across all asset types, and simplified accounting with consolidated transaction records. For DAOs and Web3 startups, the ability to manage payroll, vendor payments, and treasury from one platform eliminates the operational overhead of bridging traditional banking with on-chain activity.
Key Takeaways
- The Ripple-Privy partnership (October 13, 2026) embeds stablecoin wallets directly into apps, ending the era where stablecoins were invisible settlement rails and beginning the era where they function as consumer-facing payment methods.
- AI agents have executed 13 million payments on the XRP Ledger, representing 25% of network activity—a signal that autonomous, programmable payments are production-scale and demand operational attention from treasury teams now.
- Businesses have three integration paths for stablecoin payments: direct blockchain APIs, embedded wallet providers like Privy, or unified fiat-crypto platforms—each with distinct control, speed, and functionality trade-offs.
- Security and regulatory risk management requires more than KYC: institutional custody (e.g., Fireblocks), multi-factor authentication, and compliance with jurisdiction-specific frameworks like MiCA are table stakes.
- A unified fiat-crypto platform reduces operational complexity by collapsing custody, conversion, payments, and compliance into one interface, which is increasingly necessary as stablecoin and traditional payment flows converge.
For global businesses ready to unify their fiat and stablecoin payment operations in a single platform, explore OneSafe’s neo-banking solution.