Mastercard’s Stablecoin Platform: What It Means for Crypto Banking
Mastercard’s move into crypto banking with a dedicated stablecoin platform, built alongside crypto payments firm BVNK, marks a significant moment for businesses weighing the practical use of digital assets. The launch raises concrete questions about fees, regulation, and how quickly companies can adopt stablecoin payouts without exposing themselves to unquantified risks.
Table of Contents
- What Just Happened: Mastercard and BVNK Launch a Stablecoin Platform
- Why It Matters for Businesses Using Crypto Banking
- The Background: Crypto Banking’s Journey from Niche to Normal
- What’s Still Unknown: Fees, Regulation, and the MiCA Question
- Concrete Implications and Recommended Actions for Your Business
- What to Watch Next in Crypto Banking
- Key Takeaways
What Just Happened: Mastercard and BVNK Launch a Stablecoin Platform
What is Mastercard’s new stablecoin platform?
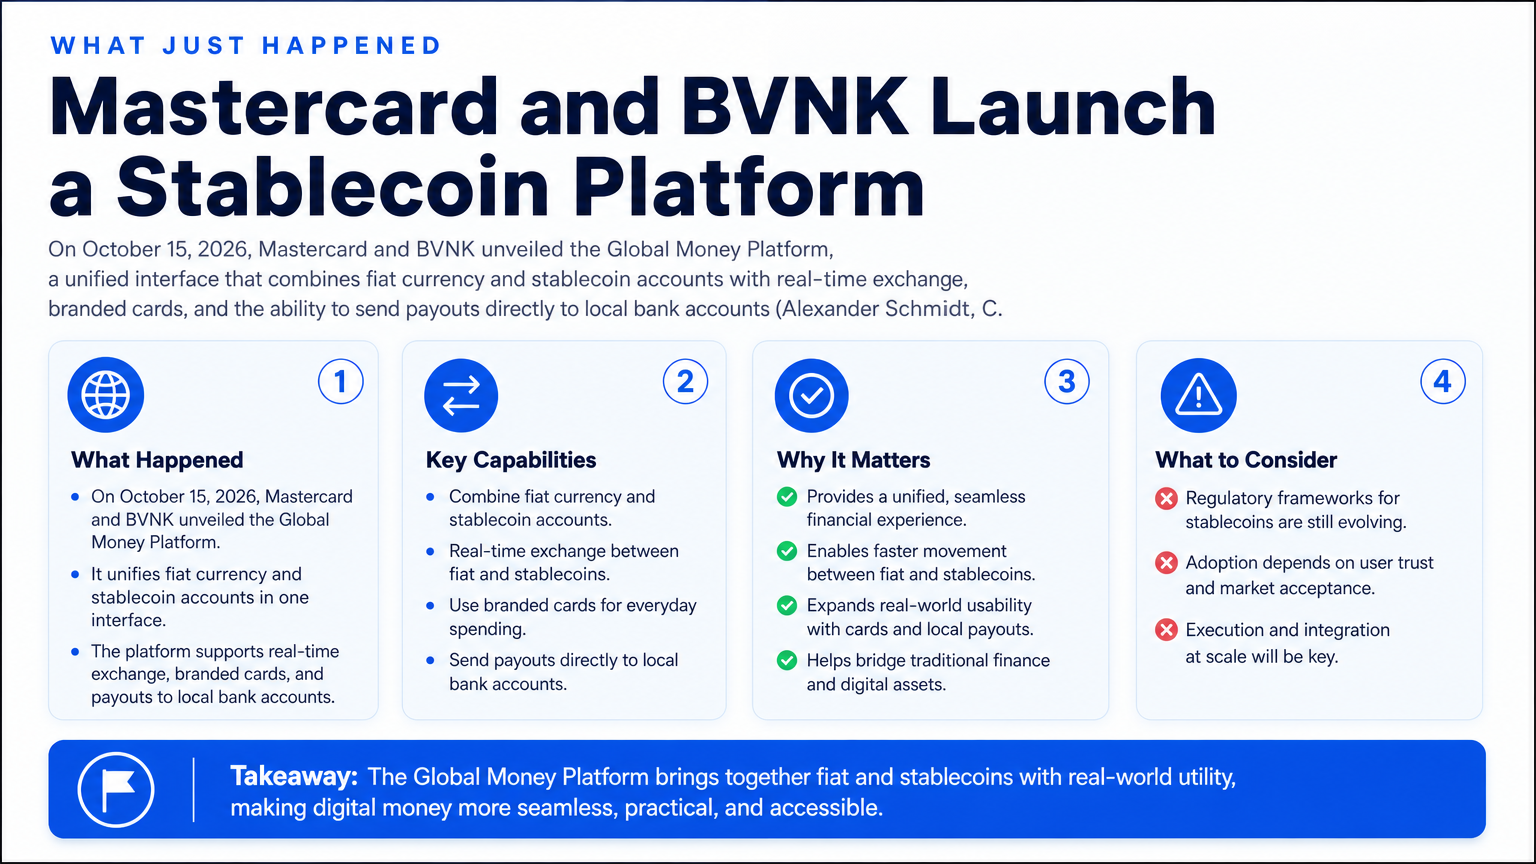
On October 15, 2026, Mastercard and BVNK unveiled the Global Money Platform, a unified interface that combines fiat currency and stablecoin accounts with real-time exchange, branded cards, and the ability to send payouts directly to local bank accounts (Alexander Schmidt, CryptoTicker, October 16, 2026). The platform is marketed as a way to handle “not just stablecoins, but every form of money,” positioning it at the intersection of traditional banking and on-chain finance.
The announcement was light on specifics: no list of supported stablecoins, no fee schedule, no mention of which jurisdictions are covered beyond the immediate note that German users face open questions around MiCA authorization. What’s clear is that a major card network is building infrastructure that treats stablecoins as a first-class payment rail, not a speculative asset.
Why It Matters for Businesses Using Crypto Banking
Why does this matter for crypto banking?
For business crypto banking, this development signals that the largest institutional players now see stablecoins as settlement-layer instruments rather than retail trading tools. Until recently, businesses wanting a crypto-friendly business account had to choose between fintechs, niche crypto banks, or keeping separate fiat and crypto stacks. Mastercard’s entry blurs that line. A business could, in theory, receive funds in USDC or another stablecoin, hold them in an account alongside euros, and pay a supplier via a card or a domestic bank transfer—all through a single provider.
The flip side is that fee opacity and regulatory unknowns turn this promise into a conditional opportunity. Without published costs, a business cannot model the economics. Without clarity on MiCA compliance, a European company risks onboarding onto a platform that might face an enforcement action later. So the immediate import is that Mastercard is legitimizing the space, but it hasn’t yet solved the friction that keeps prudent CFOs on the sidelines.
The Shift from Volatile Crypto to Stablecoin Utility
How do stablecoins reduce volatility compared to other cryptocurrencies?
Consumer crypto guides often paint the entire asset class as dangerously volatile. That narrative breaks down when the instrument in question is a fully reserved stablecoin pegged to a fiat currency. Because a well-designed stablecoin maintains a 1:1 value with, say, the US dollar, businesses can invoice, hold, and transfer value without worrying about a 20% intraday swing—something impossible with Bitcoin or Ether.
This analysis adjudicates the conflict between warnings about crypto volatility and the Mastercard/BVNK platform’s treatment of stablecoins as a stable medium of exchange: stablecoins neutralize price volatility for payments, but they introduce a different risk—compliance uncertainty. The practical consequence is that a business using stablecoin payouts on this platform faces a shifted risk landscape: less market risk, more regulatory risk.
Cross-Border Payments Get a Makeover
How can businesses use this platform for cross-border payments?
The platform’s headline feature is the ability to settle cross-border payments by converting stablecoins into local fiat and paying out to a recipient’s bank account. For a small or mid-sized business that regularly pays overseas contractors, suppliers, or affiliates, this could mean bypassing correspondent banking chains, reducing settlement time, and lowering costs—provided the fee structure is competitive.
To grasp the shift, consider the typical SWIFT wire: multi-day settlement, intermediary fees, and often a fixed cost of $25–$50 plus a percentage. Stablecoin rails can settle in minutes, and if the conversion spread is tight, the overall expense may be lower. However, as the Ripple-Convera deal showed, the advantage only materializes when the full payment stack is optimized end-to-end. Mastercard’s brand and network could push more volume onto those rails, but the fee blind spot makes comparison impossible today.
The Background: Crypto Banking’s Journey from Niche to Normal
Crypto banking once meant a handful of startup-friendly fintechs offering a segregated account where a business could hold bitcoin alongside dollars. Over the past four years, the concept has expanded to include stablecoin infrastructure layers that connect on-chain assets with traditional payment networks. Visa, for instance, now enables settlement in USDC over its own rails, and the FDIC has clarified pathways for banks to offer crypto services.
Mastercard’s platform enters this landscape not as a first mover but as a heavyweight validator. For DAO banking, in particular, where a decentralized organization might need to hold stablecoin treasuries, execute contributor payouts in fiat, and manage multi-signature access, a regulated, card-network-backed interface could simplify compliance. Yet, as the recent debanking trend demonstrates, businesses at the crypto-fiat boundary still face arbitrary account closures; a Mastercard badge does not automatically insulate against that.
What’s Still Unknown: Fees, Regulation, and the MiCA Question

The Fee Blind Spot
What are the potential fees for using a stablecoin banking platform?
The CryptoTicker report explicitly states that Mastercard and BVNK have not published fees for the Global Money Platform. Without a tariff, businesses cannot quantify the delta between using this platform and an existing provider. For reference, some neo-banking platforms serving crypto businesses disclose their charges upfront: OneSafe, for example, lists a 0.15% fee on fiat deposits and withdrawals, $25 for a wire withdrawal, and no charge for USDC deposits or withdrawals. There’s no reason to assume Mastercard’s pricing will mirror that—network-scale players often bake costs into spreads or monthly subscription fees—but until those numbers surface, any ROI calculation is guesswork.
The pragmatic posture is demand fee transparency before moving treasury flows. A stablecoin payout that appears cheap on the settlement layer could still be expensive if the conversion spread or card FX fee is wide.
| Aspect of Global Money Platform | What We Know (as of Oct 16, 2026) | What Remains Unknown |
|---|---|---|
| Launch date | October 15, 2026 (CryptoTicker) | – |
| Account types | Fiat and stablecoin accounts | Which stablecoins are supported |
| Core features | Real-time exchange, branded card, payouts to bank accounts | Geographic availability, regulatory approvals |
| Fees | Not published | Transaction fees, FX spreads, card issuance and usage costs |
| EU regulatory status | MiCA authorization not confirmed | Whether BVNK or Mastercard entity holds CASP registration |
Regulatory Uncertainty in Europe: MiCA and Beyond
What regulatory questions does MiCA raise for stablecoin platforms?
The Markets in Crypto-Assets (MiCA) regulation, fully applicable in the EU since the end of 2024, requires that any entity offering crypto-asset services—including custody, exchange between crypto and fiat, and execution of orders—must be authorized. Stablecoins that qualify as e-money tokens (EMTs) face additional capital, reserve, and redemption requirements. The CryptoTicker piece highlights that for German users, MiCA authorization is an open question for this platform.
That uncertainty is not trivial. As the USDC oversight case under EBA supervision illustrates, stablecoin issuers and distributors can find themselves suddenly under direct regulatory pressure. A business banking on a stablecoin platform that hasn’t secured proper licensing could be forced to move funds with little notice. The Stablecoin Regulation’s New Tether Test further shows that even dominant stablecoins face evolving oversight. For companies evaluating the Mastercard/BVNK offering, the key takeaway is: ask whether the platform’s stablecoin accounts and conversion services are covered by a MiCA authorization before onboarding.
Concrete Implications and Recommended Actions for Your Business
The Mastercard/BVNK launch is a signal, not a finished product. Businesses that treat it as such can prepare without overcommitting.
Evaluate Fit for Your Payment Flows
List every cross-border or supplier payment that currently incurs delays or high wire fees. Ask: would settlement in a stablecoin, converted to local fiat just before payout, improve working capital or reduce overhead? If yes, the Global Money Platform may deserve a pilot—once fees and compliance are clear. For companies already using crypto-friendly business accounts that combine fiat and stablecoin management, the Mastercard option will be mainly interesting if it delivers lower net cost or better bank integration.
Demand Clarity on Costs and Compliance
Before opening an account, request from BVNK or Mastercard’s business development team:
- A published fee schedule covering FX spreads, card usage, and account maintenance.
- Evidence of MiCA authorization for the specific entity holding customer funds in the EU.
- Confirmation of which fiat corridors and stablecoins are live, not in roadmap.
Use those answers to run a cost model comparing the platform against existing arrangements, including platforms that already handle crypto-to-fiat payroll and stablecoin payments recoverability.
What to Watch Next in Crypto Banking
How does Mastercard’s move compare to existing neo-banking solutions for businesses?
Mastercard is late to the practical crypto banking table, but its distribution muscle matters. Many neo-banking solutions—including those that serve DAOs and global startups—already offer multi-currency accounts, crypto-fiat conversions, corporate cards, and automated payouts. The difference is that Mastercard can leverage its existing issuer and acquirer relationships to make stablecoin payouts land in local bank accounts with a speed that niche players cannot always match.
The comparison isn’t about feature breadth; it’s about ecosystem integration. A DAO using a platform like OneSafe might enjoy customizable roles, Fireblocks custody, and transparent fees today, but it won’t get the automatic merchant acceptance that a Mastercard-powered card provides. The Mastercard move pushes incumbent fintechs to deepen their own stablecoin capabilities, and pushes regulators to clarify the status of these hybrid platforms. Watch for similar announcements from Visa and bank-backed consortia in the next six months, and track the first MiCA enforcement actions against stablecoin platforms—they will define the real-world risk appetite for business crypto banking.
Key Takeaways
- Mastercard and BVNK’s Global Money Platform, launched October 15, 2026, unifies fiat and stablecoin accounts with card and payout capabilities, but fee structures and MiCA authorization remain unpublished.
- Stablecoins eliminate price volatility for payments but swap it for compliance risk—businesses must treat regulatory uncertainty as a line-item risk equivalent to FX exposure.
- Cross-border stablecoin payouts hold real potential for reducing wire transfer costs and settlement times, but ROI depends entirely on undisclosed fees.
- Before adopting, demand a published fee schedule and proof of EU regulatory status, and model the platform against existing crypto-friendly business accounts that offer transparent pricing.
- The launch will pressure the whole crypto banking sector to improve integration, transparency, and compliance, benefiting businesses that can wait for the dust to settle.
If you’re evaluating how to manage fiat and crypto payments through a single, transparent platform, see how OneSafe serves global businesses and DAOs.