On October 17, 2026, KuCoin reported that MSCI finalized a rule excluding "non-operating companies" with balance sheets dominated by digital assets from its Global Investable Market Indexes. For finance teams running crypto treasury management, that announcement converts what had been an accounting and custody conversation into a capital-markets classification event. The rule, effective at the close of November 30, 2026, with affected names published November 11, 2026, does not make crypto treasuries unwise or unlawful. It does force a split every treasury should already be making: operational crypto that keeps payments running versus strategic crypto that sits on the balance sheet.
Table of Contents
- What Just Happened: MSCI Finalized Its Bitcoin-Treasury Exclusion
- Why This Matters Now for Founders and Finance Leads
- What the Current Guides Miss: Three Decisions Before November 11
- Where the Guides and the News Disagree
- Concrete Recommended Actions for Finance Teams
- What to Watch Next
- Key Takeaways
What Just Happened: MSCI Finalized Its Bitcoin-Treasury Exclusion
MSCI announced the methodology change on October 15, 2026, according to KuCoin's October 17 report. The index provider will treat "non-operating companies" as ineligible for inclusion in the MSCI Global Investable Market Indexes, finalizing an August proposal. The trigger is precise: companies with over 50% of assets in digital assets fall under the rule. KuCoin names MicroStrategy and Metaplanet as firms the rule could affect.
MSCI will publish the final list of affected companies on November 11, 2026, and the methodology takes effect at the close of November 30, 2026. Funds tracking MSCI benchmarks may have to sell shares of excluded firms, removing a key source of passive investment demand.
The MSCI decision reframes what a digital asset treasury means to capital markets. A concentrated crypto position is no longer only a volatility question for the CFO's risk register; it is now a classification event with index-eligibility consequences. What changed is not crypto's volatility but the formalization of a taxonomy in which "non-operating" balance sheets — those dominated by investment holdings rather than operating assets — lose access to passive-index flows regardless of the asset's underlying performance.
Why This Matters Now for Founders and Finance Leads
For listed companies: passive demand and forced selling risk
Shares excluded from the MSCI indexes lose the mechanical buying that index funds provide. Investors holding the stock through MSCI-linked vehicles may be forced to sell on the rebalancing date, independent of their conviction in the company's strategy. For CFOs of affected or borderline firms, the practical question is whether to reduce exposure or accept the exclusion before the November 11 list locks positions in.
For private startups and DAOs: the institutional lens is arriving
Private companies and DAOs are not directly bound by MSCI's index methodology — but the lens travels. When a major index provider classifies a balance sheet with over 50% of assets in digital assets as "non-operating," private investors, lenders, and counterparties will begin asking the same threshold question. DAO treasury management faces the same scrutiny through a different door: limited-partner allocations, lending covenants, and credit terms are unlikely to ignore an index provider's published standard.
The core reframe: operational crypto vs. strategic crypto
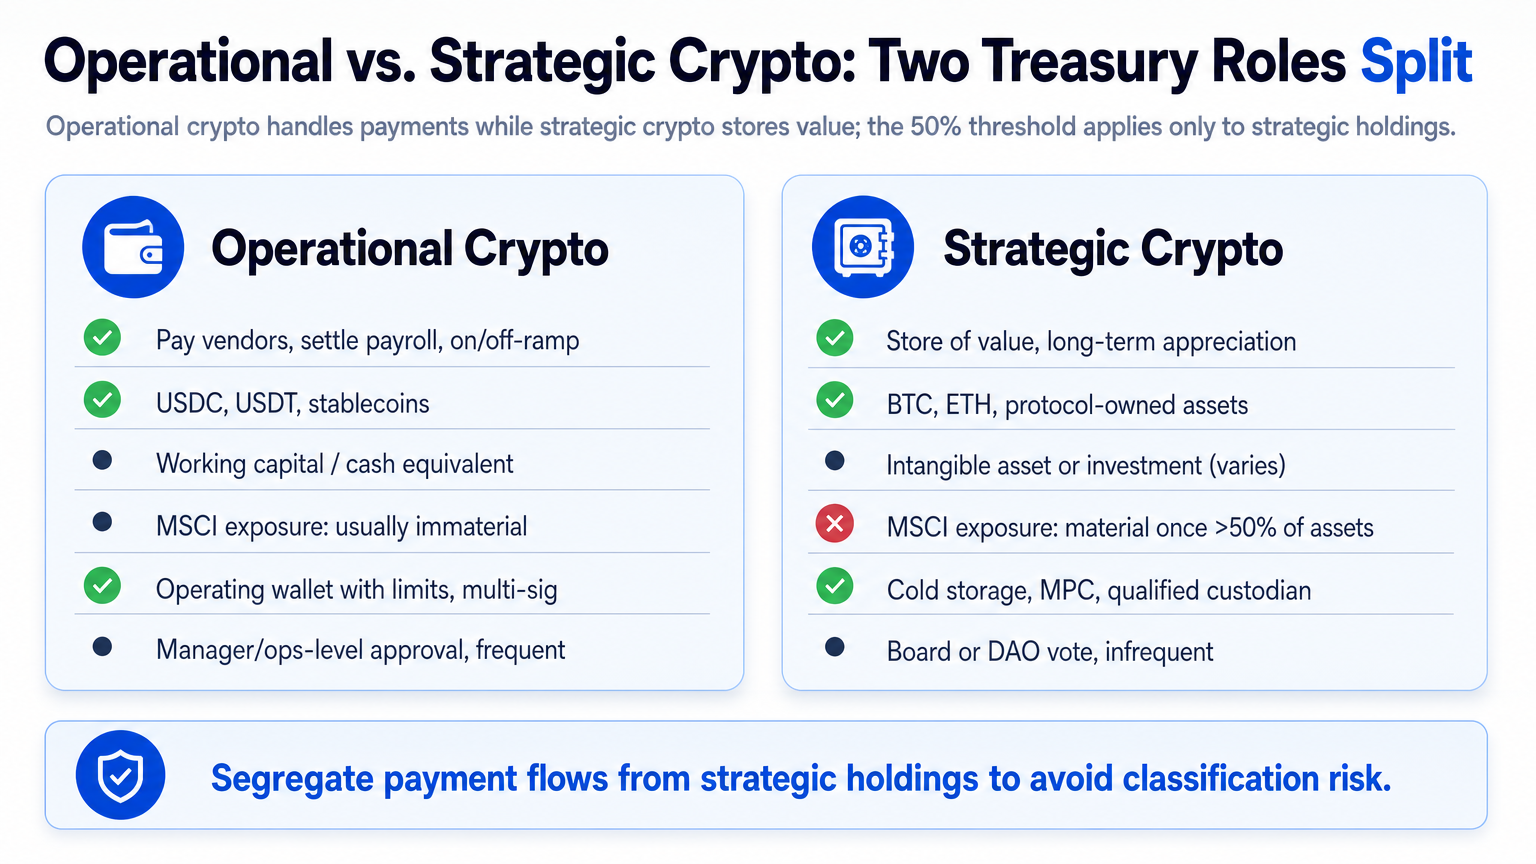
The most useful response to the MSCI rule is not to flee crypto. It is to separate the two treasury functions that current guides collapse into one.
| Treasury function | Operational crypto | Strategic crypto (bitcoin treasury) |
|---|---|---|
| Primary purpose | Pay vendors, settle payroll, on/off-ramp | Store of value, long-term appreciation |
| Typical assets | USDC, USDT, stablecoins | BTC, ETH, protocol-owned assets |
| Accounting treatment | Working capital / cash equivalent | Intangible asset or investment (varies by jurisdiction) |
| Key risks managed | Counterparty, conversion, float | Volatility, impairment, classification |
| MSCI index eligibility exposure | Usually immaterial | Material once holdings exceed 50% of assets |
| Custody style | Operating wallet with limits, multi-sig | Cold storage, MPC, qualified custodian |
| Approval workflow | Manager/ops level, frequent | Board or DAO vote, infrequent |
The 50% threshold that triggers MSCI's rule applies to the strategic bucket. But most finance teams have never documented which bucket their holdings fall into. That gap is precisely what creates urgency before November 11, 2026.
What the Current Guides Miss: Three Decisions Before November 11
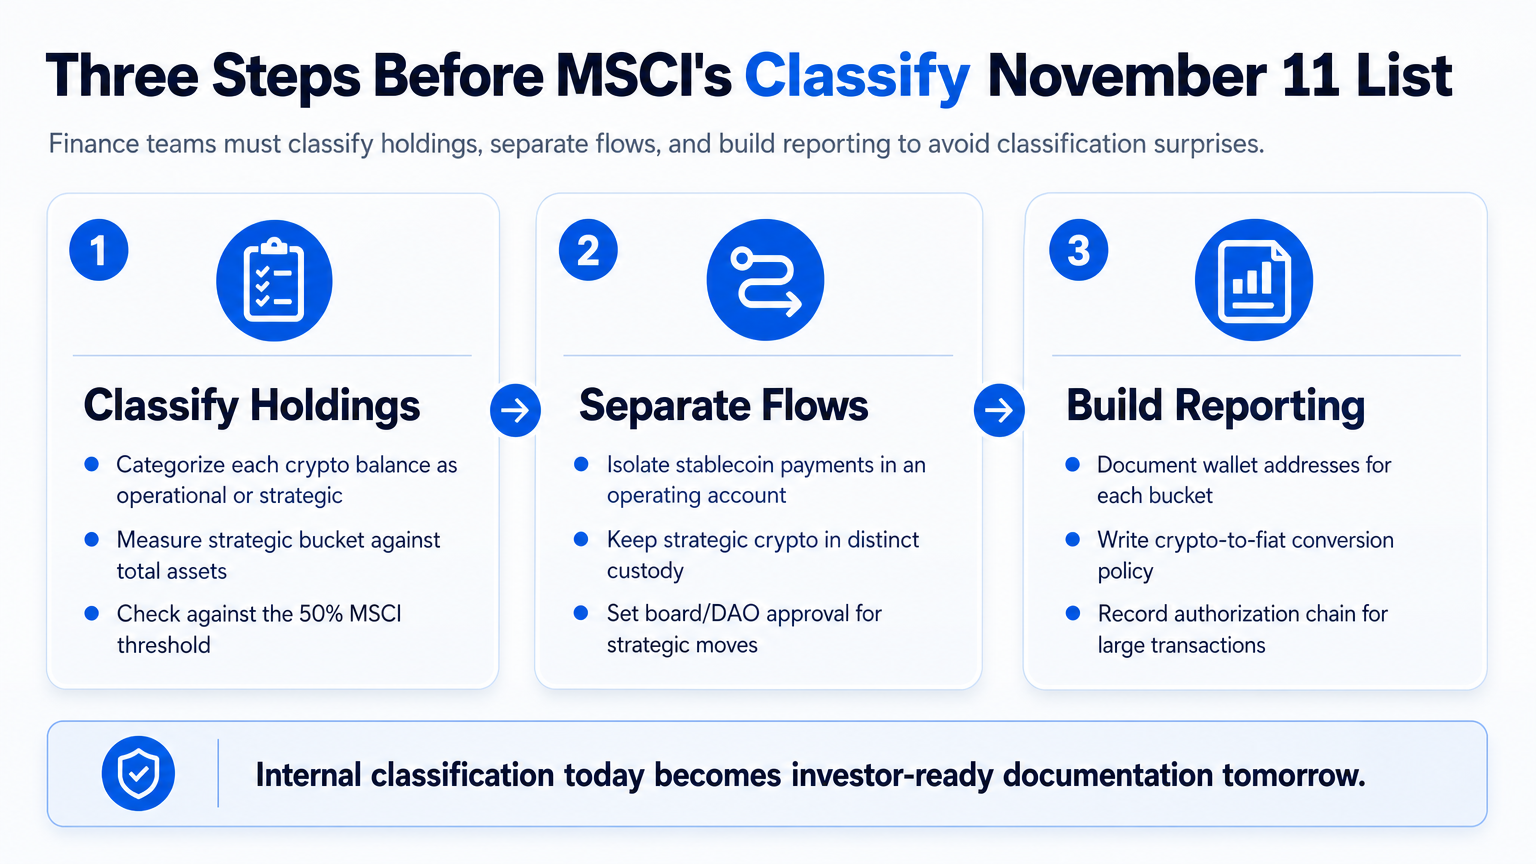
Classify your digital-asset mix against the 50% threshold
The decision rule is now explicit: over 50% of assets in digital assets triggers "non-operating" classification. Before November 11 — the date MSCI publishes its list — finance teams should classify every crypto balance as either operational crypto or strategic crypto, then measure the strategic bucket against total assets. For most private firms this is not a compliance filing; it is a conversation-ready number.
Separate payment flows from balance-sheet holdings
The cleanest way to demonstrate that a company is an operating business rather than a de facto bitcoin treasury is to keep payment flows in a separate balance from strategic holdings. Stablecoin payments for vendors and payroll should sit in an operating account with limited balances, while strategic crypto sits in distinct custody with board- or DAO-level approval. OneSafe's coverage of stablecoin payments hitting banking rails in October 2026 shows the rails exist to run USD-pegged flows through business accounts; the missing step is segregating them from long-term crypto positions. The GENIUS Act is relevant context here, as OneSafe's 2026 analysis of the GENIUS Act stablecoin regulation points out, because a defined regulatory perimeter for stablecoins makes the "operating" classification easier to defend.
Build reporting and approvals before the next investor conversation
The three pre-November-11 moves are: (1) document which wallet addresses hold strategic versus operational crypto; (2) write the crypto-to-fiat conversion policy before a cash crunch forces ad hoc sales; and (3) record the authorization chain for any move over a set threshold. These are internal documents today and investor-ready artifacts tomorrow.
Where the Guides and the News Disagree
Why pro-crypto treasury guidance and the MSCI headline can both be right
Fireblocks and Stripe have framed crypto treasury support as a broadly beneficial default for finance teams — expanded payment rails, faster settlement, lower cross-border cost. MSCI's rule, by contrast, warns that concentrated digital-asset balance sheets can produce capital-market exclusion. Both claims are true, but they describe different treasury functions.
The reconciliation rests on the operational-strategic split. The Fireblocks and Stripe thesis applies most cleanly to operational crypto flows — stablecoin payments, payroll disbursement, on/off-ramping — where crypto reduces friction without dominating the balance sheet. MSCI's warning applies to strategic bitcoin treasuries, where the asset itself is a concentrated, material position. A company can run a sophisticated stablecoin payment program and hold zero strategic crypto; it faces no MSCI exposure. A company can also run a strategic bitcoin treasury and, per the new rule, face classification consequences.
Liquidity, custody, and index risk as one framework instead of competing priorities
Request Finance's guidance prioritizes liquidity management; Fortris centers Bitcoin-specific custody; neither addresses MSCI index eligibility — the variable introduced on October 15, 2026. The correct move is to integrate the three into one framework. Liquidity covers conversion and float. Custody covers key management and loss prevention. Index and classification risk covers balance-sheet composition. Finance teams should treat these as three columns of the same treasury memo, not three vendors competing for the same budget line.
Concrete Recommended Actions for Finance Teams
Set an operational crypto ceiling and document it
Set a formal ceiling on the operational crypto balance — the maximum a payment account holds overnight or between sweeps. The ceiling converts strategy into policy and makes explicit that working capital is not being accumulated into an undeclared bitcoin treasury. The cost case for running stablecoin flows is real: OneSafe's analysis of stablecoin payments being 84% cheaper shows the pricing advantage exists. The ceiling is what prevents cost-saving payment flows from silently becoming a speculative position.
Run fiat and crypto flows through a unified operating account
The fastest way to simplify controls is to consolidate fiat and crypto flows through one operating account that supports both rails: ACH, domestic and international wires, bill payments, and instant crypto-to-fiat conversions. OneSafe is an example of a platform that combines multi-currency fiat accounts with crypto on/off-ramps and digital-asset custody via Fireblocks — but the selection criterion is mechanical, not brand-specific: the account must let finance teams see fiat and stablecoin positions in one ledger, convert without external settlement risk, and apply role-based permissions to both. The October 2026 Mastercard platform coverage and the stablecoin cards expansion illustrate how quickly the payment side is maturing; the treasury's job is to harness that without letting operational balances drift into strategic positions.
Verify custody, controls, and conversion costs before adding tools
Before selecting any tool, verify three mechanics: (1) whether digital assets are held in multi-sig, MPC, or qualified-custody architecture — never a single hot wallet; (2) whether role-based permissions separate custody from payment authorization, with multi-factor authentication enforced; and (3) what crypto-to-fiat conversion actually costs, including spreads and wire fees. OneSafe's coverage of the Deutsche Bank custody shift shows incumbents moving into custody, but depth of controls, not brand, should dictate selection.
How can finance leaders build controls for crypto treasuries?
Controls start with a written policy, not a tool. The policy should specify: which wallets are authorized for which transactions; what dollar threshold requires what approval level; who can execute crypto-to-fiat conversion; and how the audit trail is maintained. Second, enforce segregation of duties — the person initiating a payment cannot be the only person approving it, and custodial access should be separate from payment authorization. Third, run a monthly reconciliation between on-chain balances and the accounting system, using block height and transaction hash as the source of truth. Fourth, cap the operational wallet so a single compromise cannot drain the treasury.
How can organizations secure crypto assets?
The baseline, echoed across custody guides, is that material crypto holdings never sit primarily in hot wallets. Multi-signature wallets for operational balances and MPC-based or qualified-custodian storage for strategic holdings are the standard. For DAOs, the equivalent is a multi-signature treasury wallet with a minimum quorum and role-based permissions. On-chain asset custody is only as strong as the signing policy: hardware or hardware-grade key storage, withdrawal delays on strategic vaults, and multi-party approval for any move over a set threshold.
Does a crypto treasury affect index eligibility after MSCI's rule?
Yes, with a clearly delimited trigger. Under MSCI's finalized methodology, announced October 15, 2026, and effective at the close of November 30, 2026, companies with over 50% of assets in digital assets will be treated as "non-operating" and ineligible for inclusion in the MSCI Global Investable Market Indexes. The rule applies to the concentration of digital assets, not to the mere existence of a crypto treasury. CoinGecko's bitcoin treasuries tracker maps public-company holdings if you want peer benchmarks.
What tools support crypto treasury operations?
Tooling spans three layers: custody and key management (Fireblocks, BitGo, self-hosted multi-sig), treasury and payment operations (platforms that combine fiat accounts, ACH and wire rails, and stablecoin payment capabilities), and accounting/reporting (Bitwave, Request Finance, and similar systems that map on-chain activity to the general ledger). Schwab's explainer on bitcoin treasury companies helps finance teams benchmark how public peers structure the strategic side.
How do DAOs manage crypto treasury operations?
DAO treasury management runs on the same operational logic with different governance. Multi-party approval workflows replace a single CFO sign-off; on-chain transparency replaces internal audit; and role-based permissions, often enforced at the wallet or contract level, implement segregation of duties. OneSafe is an example of a platform that adds customizable roles and permissions for DAO treasury operations, with digital assets secured through Fireblocks — relevant not because of the brand but because the core DAO requirement is granular, enforceable permissions linked to the multisig. The MSCI rule does not directly apply to token-holder structures, but the classification logic — separating working capital from strategic holdings — transfers cleanly to a DAO balancing a stablecoin treasury for contributor payments against long-term protocol-owned crypto.
What to Watch Next
November 11: the final list of affected companies
MSCI will publish the final list of affected firms on November 11, 2026. For listed companies near the threshold, the list converts the August proposal into named, index-level consequences — and triggers the passive-selling mechanics that funds must execute before the effective date. Finance teams should watch not only whether their firm appears but whether peers' appearances change how lenders and investors value comparable balance sheets.
November 30: the rule takes effect
The methodology change is effective at the close of November 30, 2026. The gap between November 11 and November 30 is the practical window: funds tracking MSCI benchmarks will position ahead of the effective date, so share-price effects, if any, may precede the formal cutoff.
Open questions: will other index providers follow, and will private investors copy the lens?
The open question is whether FTSE Russell, S&P Dow Jones, or national index providers adopt a similar "non-operating" classification for digital-asset-heavy balance sheets. If they do, the 50% threshold becomes a de facto capital-market standard rather than a single index provider's rule. The second open question is transmission to private markets: whether venture investors and lenders write the 50% threshold, or a tighter version of it, into terms sheets and loan covenants. Both outcomes are plausible. Neither is confirmed as of October 17, 2026.
Key Takeaways
- The MSCI rule, announced October 15 and effective November 30, 2026, classifies companies with over 50% of assets in digital assets as "non-operating" and excludes them from the Global Investable Market Indexes — a liquidity event driven by classification, not fundamentals.
- Split crypto holdings into operational crypto (stablecoin payments, working capital) and strategic crypto (bitcoin/ETH treasury positions), and measure the strategic bucket against total assets immediately.
- Before November 11, document the digital-asset mix, separate payment flows from balance-sheet holdings, and build the reporting and approval artifacts investors will ask for.
- Treat liquidity, custody, and classification risk as three columns of one treasury framework rather than competing vendor pitches.
For finance teams that want one place to run fiat and crypto operations with the account, conversion, custody, and permission controls this reclassification demands, open a OneSafe account.