

On October 14, 2026, the European Banking Authority (EBA) classified USDC as a significant e-money token under the Markets in Crypto-Assets Regulation (MiCA). From November 12, 2026, the EBA assumes direct, pan-European supervision of the stablecoin’s reserves, own funds, and liquidity management—replacing the Autorité de Contrôle Prudentiel et de Résolution (ACPR), the French national supervisor that previously handled this role. The move crystallizes a shift in stablecoin regulation that every business holding or transacting in USDC must now prepare for.
Table of Contents
- What Just Happened: EBA to Supervise USDC Starting November 12
- Why This Moment Matters for Global Businesses
- The Background: Stablecoin Regulation Before This News
- Concrete Implications for Businesses Holding or Transacting in USDC
- Open Questions and What to Watch Next
- Key Takeaways
What Just Happened: EBA to Supervise USDC Starting November 12
The October 14 Classification and MiCA’s Trigger
Under Article 56 of MiCA, the EBA assessed USDC and concluded it qualifies as a significant e-money token—the first such designation in the European Union. The determination triggers enhanced prudential requirements beyond those for standard e-money tokens. Circle must now meet higher capital, liquidity, and reporting standards, and the EBA itself takes over ongoing supervision rather than merely coordinating national authorities. The change becomes effective November 12, 2026.
From National Watchdog to Pan-European Authority
Before this decision, Circle’s EU operations were supervised at the national level by the ACPR under a transitional arrangement. With MiCA in full application, the EBA’s direct oversight now means a single, centralized examination of the issuer’s compliance across all EU member states—no room for regulatory arbitrage. For businesses, that signals a more uniform enforcement posture and a more demanding one.
Why This Moment Matters for Global Businesses
USDC’s Role in Cross-Border Commerce and Treasury
USDC is deeply embedded in business payments, treasury management, and DeFi. Its multi-billion-dollar market cap is used daily for cross-border settlements, crypto payroll, and as a bridge currency in trading. Any regulatory change to its operational foundation therefore ripples through corporate treasuries worldwide. Companies with European subsidiaries, suppliers, or banking partners now find their go-to stablecoin entering a stricter supervisory regime.
A New Layer of Compliance for Non-EU Companies
Non-EU businesses that custody USDC with EU-based exchanges or custodians, or transact with European counterparties, will feel the secondary effects. European service providers must now ensure the stablecoin they handle meets the EBA’s heightened disclosure, liquidity, and redemption standards. That can lead to re-evaluated counterparty risk profiles, revised service agreements, and possible delisting if the provider cannot demonstrate compliance. In short, cross-border stablecoin compliance just became materially more concrete. Treasury teams navigating these shifts are also rethinking banking relationships—see Debanking Drives Crypto Treasury Management Adoption.
The Background: Stablecoin Regulation Before This News

The Pre-MiCA Patchwork: US vs. EU Approaches
Before MiCA, the EU lacked a unified framework. Stablecoin issuers navigated a patchwork of national e-money licenses, while the US relied on state-level money transmitter laws and evolving federal guidance. The US GENIUS Act, signed in 2025, is now being implemented through proposed rules by the Treasury and the OCC (see the Federal Register notice and an OCC bulletin). The EU’s MiCA, by contrast, creates a single passport for crypto-asset service providers and explicitly regulates e-money tokens, with tiered rules for “significant” tokens administered directly by the EBA.
Key Pillars of MiCA for E-Money Tokens
Under MiCA, an e-money token must be issued by an authorized credit institution or e-money institution, be redeemable at par at any time, and maintain a reserve of assets at least equal in value to tokens in circulation. When a token crosses certain thresholds—such as 10 million holders or a market capitalization above €5 billion—it becomes a “significant” e-money token and falls under EBA supervision with stricter requirements. The USDC significant token designation activates those enhanced obligations.
Concrete Implications for Businesses Holding or Transacting in USDC
What does the EBA's new role mean for businesses holding USDC?
Directly, few obligations fall on end-user businesses that simply hold USDC in a non-custodial wallet. But any company using EU-based custodians, exchanges, or payment processors will see those providers tighten compliance checks. Banks providing on/off-ramp services for USDC may request additional attestations about the issuer’s reserve composition and liquidity. Treasury teams reporting under EU accounting standards may also need to reassess USDC’s classification as a cash equivalent—the heightened supervision adds positive signals about asset backing but introduces new disclosure considerations.
How will MiCA change stablecoin usage in Europe?
MiCA will not ban USDC; it legalizes and normalizes its use—provided Circle meets the enhanced standards. The practical effect is a regulated market where businesses can hold and transact USDC with confidence that the token is backed by liquid, high-quality reserves and subject to regular audits. The trade-off is cost: higher compliance expenses could flow through to issuance fees or redemption processes. Some smaller European exchanges may decide the cost of maintaining access to a significant token is too high, potentially narrowing fiat-to-USDC ramps. Some EU member states are also layering national tax measures on top of the EU framework; for more, see Stablecoin Regulation: France’s 31% Tax Plan Explained.
Is USDC now fully regulated in the EU?
No—with nuance. USDC is not fully regulated in the sense that the MiCA regime is only now being fully applied. Circle must still demonstrate ongoing compliance with the EBA’s requirements, including detailed reserve reports and liquidity buffers. The significant designation is the starting point, not the finish line. Operationally, however, USDC can now be offered across the EU under a unified regulatory umbrella, which de-risks its use compared with the previous nationally fragmented status.
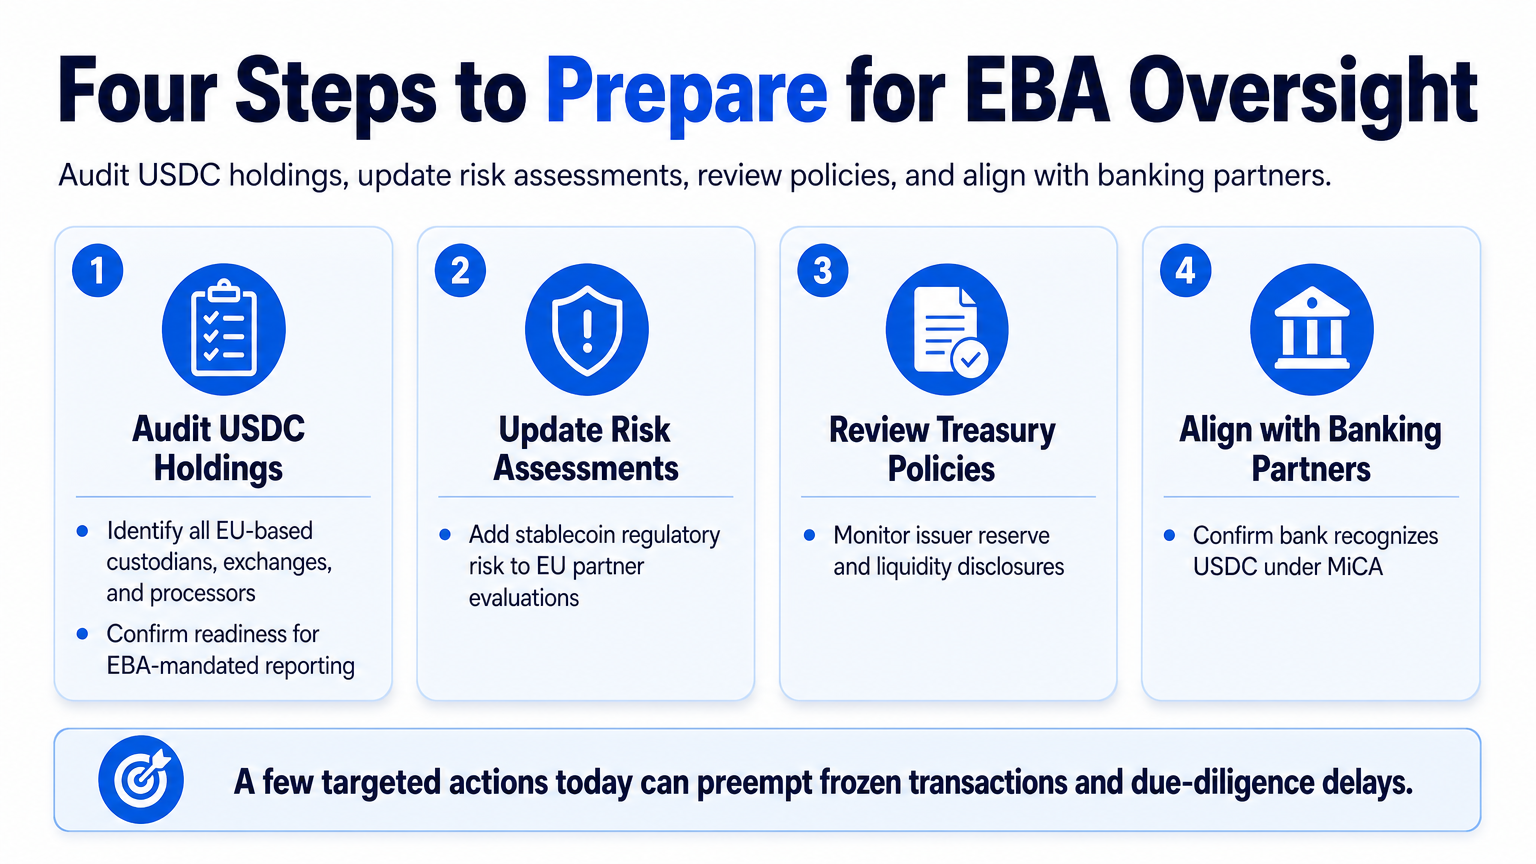
What should businesses do to prepare for November 12?
The transition on November 12 is less about a sudden imposition of new rules and more about the activation of direct EBA oversight. This checklist covers the key near-term actions:
| Step | Action |
|---|---|
| 1. Audit USDC holdings and providers | Identify all EU-based custodians, exchanges, and payment processors that touch your USDC; confirm readiness for EBA-mandated reporting. |
| 2. Update counterparty risk assessments | Add a line item for stablecoin regulatory risk when evaluating EU partners. |
| 3. Review treasury and compliance policies | Reference the new EBA oversight and define how you will monitor issuer reserve and liquidity disclosures. |
| 4. Align with banking partners | Confirm your bank recognizes USDC under MiCA to pre-empt frozen transactions or enhanced due-diligence holds. |
How does the EBA's supervision affect USDC's safety and liquidity?
The EBA’s direct oversight is designed to enhance safety. For a significant e-money token, the issuer must maintain own funds equal to at least 2% of the average outstanding amount of the token, plus a liquidity buffer that ensures continuous redemption in both normal and stressed conditions. The EBA can demand intraday liquidity reporting and impose redemption gates if reserves fall below requirements. For businesses, this means a lower probability of a run that freezes redemptions—critical when USDC is used for time-sensitive payroll or settlement. The trade-off is a more conservative asset mix, potentially reducing yields the issuer could otherwise pass on to holders, though USDC itself does not pay yield.
What are the reserve requirements for significant e-money tokens under MiCA?
Under MiCA, all e-money tokens must be backed by a reserve at least equal to the face value of tokens in circulation. For significant tokens, the rules go further:
- Reserves must be segregated with EU credit institutions or central banks, or invested in secure, low-risk assets.
- At least 30% of the reserve must be in highly liquid assets, with composition closely monitored.
- Issuers must publish a monthly audited reserve attestation and a quarterly breakdown by asset type, maturity, and counterparty.
- A liquidity coverage requirement ensures redemptions can be met within one business day under normal market conditions, even during a partial run.
These stablecoin reserve requirements are substantially more rigorous than provisional attestations, and the EBA’s oversight adds enforcement teeth.
Does this affect USDC's peg to the US dollar?
The peg is a function of market confidence and the issuer’s ability to honor redemptions at $1.00. The EBA’s supervision does not directly change the peg mechanism, but it strengthens trust that USDC will be fully backed by liquid, high-quality assets. That should support, not undermine, the peg. If the issuer faces constraints on how it deploys reserves, that could modestly affect the yield generated on reserves, but not the 1:1 redeemability. So the answer is: no, the peg itself is not affected, but the structural assurance behind it is reinforced.
How does this compare to US stablecoin regulation?
The US approach, as of late 2026, remains state-centered with a federal overlay still unfolding. The GENIUS Act established a framework for federal- and state-chartered stablecoin issuers, but detailed rules on reserve composition and capital are still being refined—the Treasury sought public comment on proposed regulations in late September 2026, as noted in this Treasury release. In contrast, the EBA’s direct supervision of USDC is federal, uniform, and already in force. For businesses, the EU now offers a more predictable compliance environment for stablecoin activity than the US, though both are converging.
Open Questions and What to Watch Next
Will USDC Expand Its Euro Basket Peg?
Circle already issues Euro Coin (EUROC) as a separate euro-backed stablecoin. The EBA designation may accelerate plans for a euro reserve component or a MiCA-compliant euro stablecoin, but no formal announcement has been made. Businesses that settle in euros should watch whether Circle uses its new regulatory footing to launch a euro-denominated product with direct EBA oversight, potentially simplifying hedges and FX costs.
Other Stablecoins in the EBA’s Crosshairs
USDC is the first, but likely not the last. Tether’s EURt and other large-cap stablecoins could face similar significant-token designations if they meet MiCA thresholds. The EBA is reviewing several token issuers. For businesses, stablecoin regulation 2026 is a moving target: holding multiple stablecoins means tracking a growing list of supervised tokens and their risk profiles.
The Ripple Effect on US and Global Regulation
The EBA’s move may embolden other jurisdictions. The UK’s forthcoming stablecoin regime and Japan’s already strict rules could converge around common reserve and supervision standards. In the US, the Treasury’s proposed rules echo some MiCA capital requirements but stop short of creating a dedicated federal supervisor. As global standard-setters like the BIS and FSB weigh in, the EBA’s hands-on approach could become a template. For multi-jurisdiction businesses, the next 12 months will likely bring more cross-border harmonization pressure.
Key Takeaways
- USDC becomes directly supervised by the EBA on November 12, 2026, elevating reserve and liquidity obligations and bringing a single enforceable standard across the EU.
- Businesses should audit USDC-related service providers, update counterparty risk frameworks, and confirm banking partners’ readiness before the transition date.
- The significant e-money token designation does not threaten USDC’s dollar peg; it strengthens credibility by enforcing MiCA’s reserve and capital rules.
- The EU now provides a more uniform compliance environment than the still-evolving US state-federal patchwork, though both systems are converging.
- Platforms that integrate fiat and crypto operations can help companies adapt by consolidating compliance monitoring, FX, and custody into one interface.
For businesses that manage both fiat and stablecoin flows across borders, staying ahead of these regulatory shifts is easier with a unified financial platform. Open a OneSafe account today to streamline your global payments and compliance.



