Stablecoin Regulation: EU Takes Direct USDC Oversight
On October 14, 2026, the European Banking Authority classified USDC as a “significant” e-money token under MiCA—the first operational shift of stablecoin regulation from policy paper to direct supervision. As Startup Fortune reported on October 18, 2026, the change takes effect November 12, 2026. Circle’s USDC, with reserves near $77 billion, will answer to the EBA for own funds, reserve assets, liquidity, and redemption plans, not just France’s ACPR. For any business that holds, pays, or settles in digital dollars, that changes counterparty risk math.
Table of Contents
- The EBA’s Direct USDC Oversight: A Regulatory First
- Why This Shift Matters for Businesses Using Stablecoins
- Stablecoin Regulation 101: The Global Landscape
- How Neo-Banking Platforms Are Adapting to New Stablecoin Rules
- What Businesses Should Do Now to Prepare
- What’s Next: Open Questions and Upcoming Deadlines
- Key Takeaways
The EBA’s Direct USDC Oversight: A Regulatory First
What just happened with USDC regulation in the EU?
On October 14, 2026, the EBA classified USDC as a “significant” e-money token under MiCA, effective November 12, 2026. Direct supervisory power over USDC’s own funds, reserve assets, liquidity requirements, and recovery and redemption plans moves from France’s Autorité de Contrôle Prudentiel et de Résolution to the EBA. Circle Internet Financial Europe SAS registered in France last year; the ACPR arrangement remains for the other 44 MiCA-notified e-money tokens. USDC is the first to cross the significance threshold.
What the October 14 announcement actually says
The announcement does not ban USDC, freeze reserves, or immediately impose a new reserve ratio. It shifts supervision from a national regulator to an EU body and brings USDC under more intensive oversight for systemically important e-money tokens. The EBA will now directly scrutinize reserve composition, liquidity management, redemption operations, and recovery planning. For businesses, the practical effect is that a single EU authority—not a member-state regulator—will enforce consistent standards.
How ‘significant’ status moves supervision from national to EU level
Most MiCA e-money tokens are supervised by their home national authority. Once deemed significant—based on scale, customer usage, cross-border activity, and interconnectedness—the EBA takes direct responsibility. The shift reduces jurisdiction-by-jurisdiction variation and means bigger issuers get stricter, centralized oversight. France’s regulatory trajectory remains part of the business calculus, as this separate look at France’s stablecoin regulation vote explains.
Why This Shift Matters for Businesses Using Stablecoins
Why does the EBA taking over USDC oversight matter for my business?
If your business holds USDC as operating float, settles vendor payments with it, or accepts it from customers, direct EBA oversight changes who supervises redeemability. Instead of a national supervisor, the EU banking regulator now controls the reserve and redemption framework. That should mean more uniform enforcement and faster intervention, but issuers may adjust reserve management, redemption processing, or compliance practices. Treasury teams should not assume the operational status quo continues unchanged.
Reserve requirements, liquidity buffers, and your redemption rights
MiCA already requires e-money token reserves to be fully backed, held in safe and liquid assets, and segregated. For a significant token, the EBA has a stronger mandate to check reserve management and ability to absorb redemption spikes. The clearest implication for users is redemption certainty. EBA oversight is not a deposit guarantee, but it reduces the chance of a local supervisor overlooking reserve mismatches.
How stablecoin regulation affects daily treasury operations and payment flows?
For corporate treasurers, the most visible effect is procedural. If an issuer tightens redemption windows, imposes larger minimum redemptions, or shifts reserve custodians to satisfy the EBA, payment flows can slow at the edges. A business relying on same-day USDC settlements may need larger fiat buffers during the transition.
How payment flows and settlement finality could change
Payment flows built on USDC rails—including Visa’s stablecoin payment production rollout—rely on confidence that a stablecoin will redeem at par. Direct EBA oversight should strengthen that confidence, but it also introduces more regulatory friction for payment providers. Some may pass compliance costs through in settlement fees or onboarding requirements. On-chain finality remains fast; the downstream fiat leg may get more scrutinized. For the card-network picture, see Mastercard’s stablecoin payments move.
The compliance signal: no more tier-one-by-jurisdiction loopholes
The USDC decision signals that a token’s global size can trigger EU-level supervision regardless of where its issuer is licensed inside the bloc. The playbook of choosing an issuer based on a lighter national regime is shrinking. The stablecoin compliance benchmark is now systemic footprint, not home regulator reputation.
Stablecoin Regulation 101: The Global Landscape
What are the key global stablecoin regulatory frameworks I need to know?
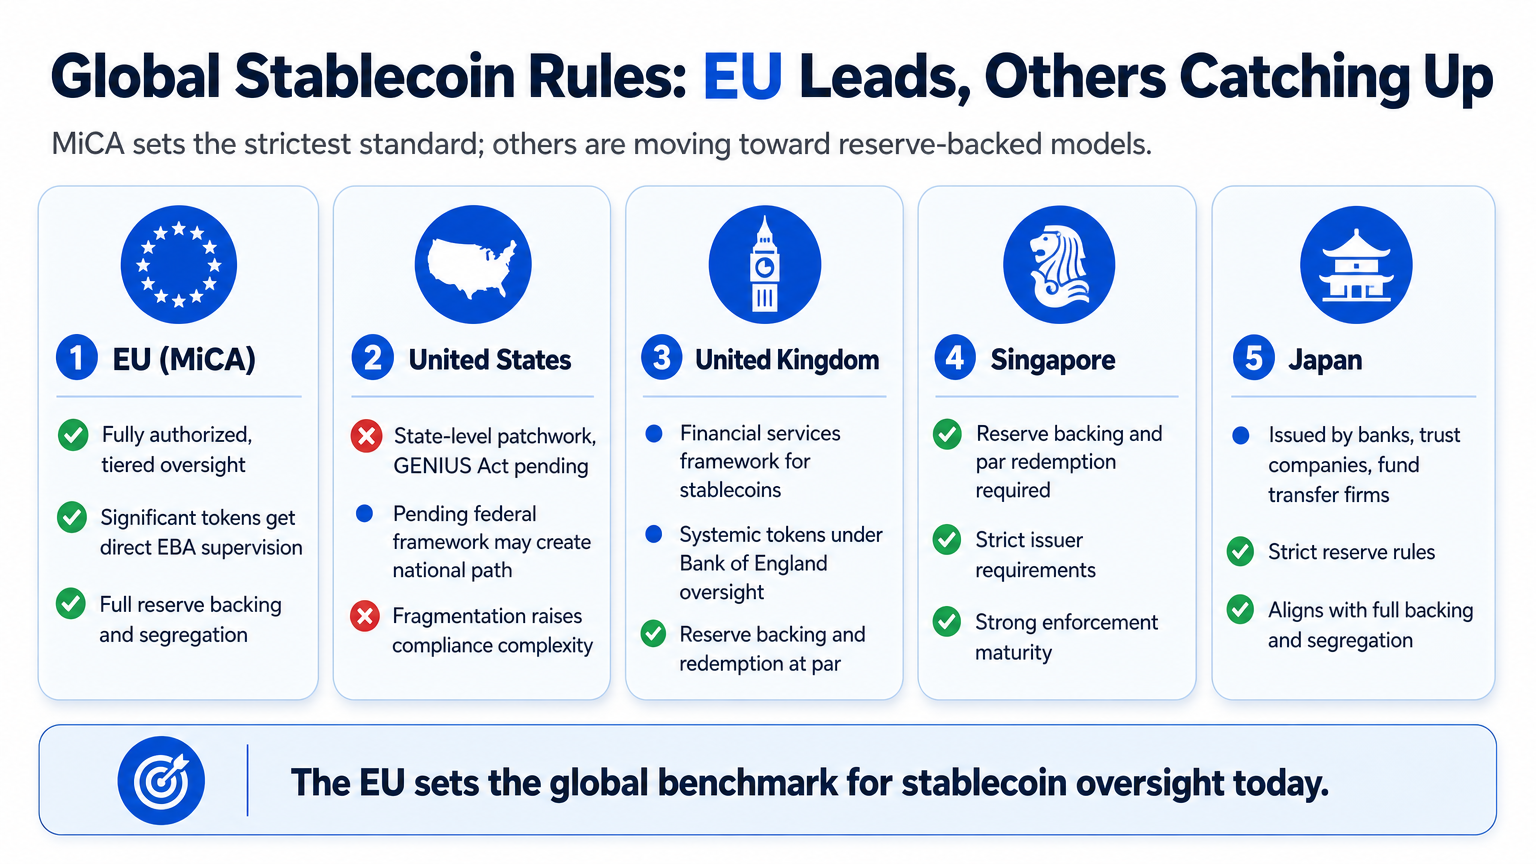
The main frameworks are not identical. MiCA is the most developed: authorization, reserve coverage, and tiered supervision. The US is fragmented across state money transmitter regimes with pending federal legislation. The UK, Singapore, and Japan are moving toward reserve-backed models but less far along. For a global business, the strictest regime you can receive payments from tends to set the compliance floor.
US fragmentation and the GENIUS Act’s promise of a federal floor
US stablecoin issuers currently face a state money transmitter patchwork. The GENIUS Act, a pending federal bill, would create a national framework for reserve-backed payment stablecoins, with federal and state paths. A Visa analysis frames this as evolution toward stronger oversight. The bill has not become law, and state fragmentation remains. Businesses should track how its final form interacts with international regimes. See our earlier analysis of how the GENIUS Act is shaping stablecoin adoption.
MiCA’s tiered model: what ‘significant’ triggers in practice
MiCA’s significance threshold is not vague. The European Parliament has described the stablecoin market as combining payment utility with run risk, which is why the regime escalates oversight at systemic scale. In practice, significance triggers direct EBA supervision, stricter liquidity and own-funds expectations, and higher reporting frequency. USDC is the first to hit that bar; others may follow.
Other key jurisdictions: UK, Singapore, Japan (snapshot)
The UK has introduced a financial services framework for fiat-backed stablecoins, aiming to bring systemic payment tokens under Bank of England oversight. Singapore requires reserve backing and timely redemption at par. Japan allows banks, trust companies, and fund transfer providers to issue stablecoins under strict reserve rules. All share MiCA’s direction: full backing, segregation, and redemption clarity. Differences lie in scope and enforcement maturity.
How Neo-Banking Platforms Are Adapting to New Stablecoin Rules
How do platforms like OneSafe help businesses navigate regulatory changes around stablecoins?
A business does not need to become a stablecoin compliance function on its own. Neo-banking for crypto platforms that natively handle fiat and crypto can absorb operational burden by providing custody, segregated accounts, and KYB onboarding aligned with regulated partners. OneSafe offers unified fiat and crypto treasury operations, with USDC deposits and withdrawals at no crypto-side fee and digital assets secured on Fireblocks. That reduces the number of separate banking and custody relationships to monitor as EU stablecoin rules tighten.
Infrastructure that bakes in compliance: custody, attestations, MFA
Custody is the key infrastructure layer. If digital assets are held in segregated, institutional-grade custody with enforced multi-factor authentication, a business has better evidence of control and ownership when a regulator or counterparty asks. OneSafe mandates MFA on signup and uses Fireblocks for digital asset custody. These are baseline controls, not optional add-ons.
Why unified fiat-crypto platforms reduce regulatory surface area
Operating stablecoin and fiat flows across multiple banks and exchanges multiplies counterparty risk assessments, reserve attestations, and redemption checks. A unified global business crypto banking platform can consolidate those flows into one interface, with one onboarding process and one set of compliance rules. The issuer’s MiCA status still applies, but internal complexity drops and audits become more tractable.
Inside OneSafe’s approach: Fireblocks custody, KYB, and segregated global accounts
OneSafe is a financial technology company, not a bank; banking services are provided by its partners. The platform provides multi-currency accounts, corporate cards, wire and ACH support, and crypto on/off-ramps in one place. For DAOs treasury management, OneSafe offers customizable roles, permissions, secure custody, and automated payment workflows. It has processed over $800 million in transaction volume from more than 1,000 businesses across 30+ countries. The same discipline now matters for on-chain organizations; see Institutional DeFi Compliance: What $500M Commitments Mean.
What Businesses Should Do Now to Prepare

What should my business do to stay compliant with evolving stablecoin rules?
Three actions are worth taking before the November 12 transition: audit stablecoin exposure, demand contractual clarity on redemption and liquidity, and choose financial partners with built-in regulatory alignment.
| Action | What to check | Why it matters now |
|---|---|---|
| Audit stablecoin exposure | Total USDC held across wallets and accounts; percentage of operating float | Direct EBA oversight may change issuer reserve or redemption practices |
| Demand contractual clarity | Issuer redemption terms, reserve attestation cadence, liquidity buffer commitments | Your ability to exit at par depends on these terms, not on brand reputation |
| Choose partners with built-in alignment | Custody arrangements, KYB standards, segregated account structure, jurisdiction of partners | Reduces the number of manual compliance checks your team must run |
Audit your stablecoin exposure and issuer concentration
What share of liquid operating cash sits in USDC versus fiat? If high, model a 48-to-72-hour redemption delay during transition periods. Even if redemptions remain instant, operational changes at the issuer or its custodians can create friction. Concentration in a single stablecoin is a separate risk; review both. Treasury teams can apply the same discipline outlined in this crypto treasury management analysis.
Demand contractual clarity on redemption and liquidity
Do not rely on marketing language. Ask your banking or payment partner for the actual redemption process, any minimum or maximum thresholds, and how they obtain proof of reserves. If the partner uses USDC for settlement, contracts should specify what happens if redemption terms change or reserves fall short. See our earlier note on stablecoin risk in crypto banking for the questions that matter before a liquidity event.
Choose banking partners with built-in regulatory alignment
A banking partner that can handle fiat and crypto natively reduces the chance that a compliance shift forces redoing onboarding or migrating accounts. Look for segregated global accounts, explicit custody arrangements, and MFA-enforced access. Those controls align with the direction of EU stablecoin rules and EBA-level supervision.
What’s Next: Open Questions and Upcoming Deadlines
Will other major stablecoins hit the MiCA significance threshold?
USDC was the first of 45 MiCA-notified e-money tokens to cross the threshold. The EBA’s decision does not name others, but the criteria—scale, customer usage, cross-border activity—suggest any token with comparable reserve size and payment volume will be reviewed. Treat the USDC decision as a template, not an isolated event.
The November 12 transition date and what to monitor
Direct supervision shifts November 12, 2026. After that date, watch for changes in USDC reserve reporting, redemption processing times, and EBA guidance on liquidity buffers. Also monitor whether Circle adjusts its EU issuance structure or reserve custodian arrangements in response to EBA oversight.
How GENIUS Act negotiations could reshape the playing field by Q1 2027
If the GENIUS Act moves through US legislative negotiations, a federal stablecoin framework could change the competitive balance between US-issued and EU-issued dollar stablecoins by early 2027. Any US federal floor would likely set reserve, redemption, and segregation standards that interact with MiCA’s tiered model. For now, the only confirmed event is EU direct USDC oversight effective November 12.
Key Takeaways
- USDC became the first MiCA-notified e-money token classified as “significant,” shifting direct reserve and redemption oversight from France’s ACPR to the EBA effective November 12, 2026.
- For treasury teams, the practical risk is not on-chain finality but redemption certainty, reserve transparency, and possible operational friction during transition.
- Global stablecoin regulation is moving toward full reserve backing, segregation, and stricter scrutiny of systemic tokens, with the EU setting the most concrete operational benchmark.
- Businesses should audit USDC concentration, demand contractual redemption terms, and work with financial platforms that already bake custody and compliance controls into infrastructure.
- Open questions remain on whether other stablecoins cross the MiCA significance threshold and how a potential US federal framework will interact with EU rules by Q1 2027.
Ready to run fiat and USDC operations from one place? Explore OneSafe.