On October 12, 2026, Bulgaria’s Fibank (First Investment Bank) signed an agreement that puts crypto banking headlines back on the map. The bank partnered with Bitpanda Enterprise to embed digital-asset trading inside its My Fibank mobile app. For over one million business and personal customers, the promise is fiat and crypto in one interface. The deal is a flashbulb for European crypto banking, but it is not a business banking signal.
Table of Contents
- What just happened in crypto banking
- Why this matters for crypto banking now
- The background: how banks are approaching crypto
- What business and DAO finance leads should do with this
- What to watch next and open questions
- Key Questions About Crypto Banking and the Fibank-Bitpanda Deal
- Key Takeaways
What just happened in crypto banking
The Fibank-Bitpanda agreement announced October 12, 2026
Fibank and Bitpanda Enterprise announced the partnership on October 12, 2026, making Fibank the first Bulgarian bank to embed crypto trading in its own app. Bitpanda acts as sole provider of trading, custody, and crypto-specific regulatory permissions. The service will run 24/7 inside My Fibank with a €1 minimum entry point. The agreement was confirmed in a PRNewswire release and reporting by FinanceX Magazine.
What is live now versus the early 2027 rollout
This is not live. It is a commercial agreement with a 2027 target. The consumer-facing service is expected in early 2027, subject to per-user approval. Until then, Fibank supplies distribution, brand, and customers; Bitpanda supplies trading infrastructure, custody, and all crypto permissions. Customers who opt in will agree to Bitpanda’s separate terms. If a custody or trading dispute arises, the customer deals with Bitpanda, not the bank.
Why this matters for crypto banking now

First Bulgarian bank embeds digital-asset trading in its own app
Fibank’s move is a regional first. No other Bulgarian bank has placed crypto trading inside its native mobile app. Even modest opt-in from its customer base would push assets onto a regulated crypto venue inside a bank-branded environment.
What a mid-tier European bank partnership signals
Mid-tier banks face pressure to offer sticky digital services. Embedding crypto through a partner is a low-capital, fast-to-market path other regional banks may follow. This mirrors white-label crypto infrastructure already plugged into banking apps in Austria and parts of Germany. See Sberbank’s crypto banking win.
Consumer trading headlines do not equal business crypto accounts
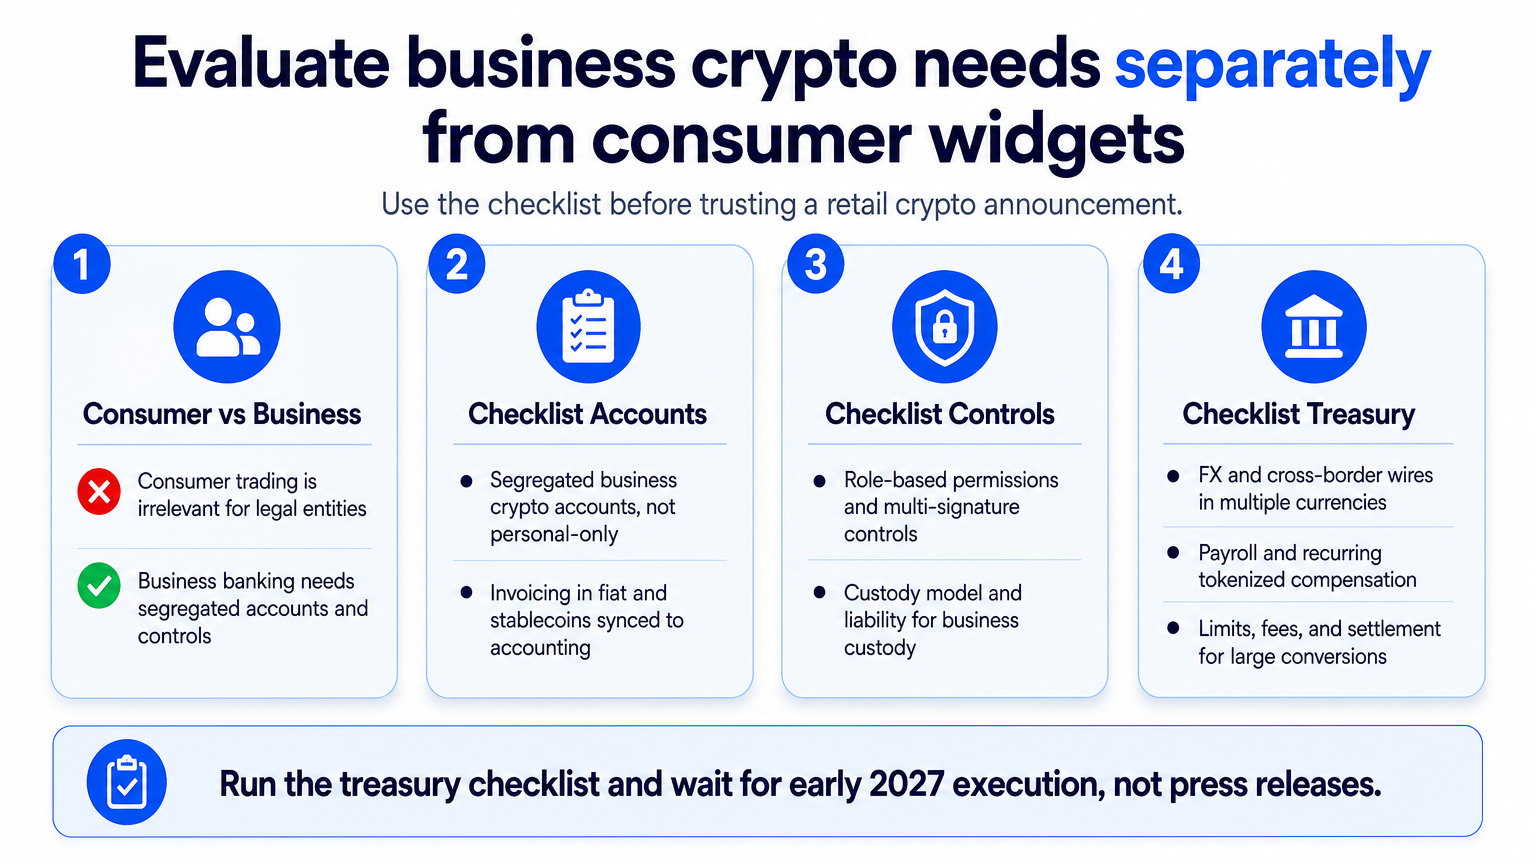
A consumer buy/sell widget is not a business crypto account. Business crypto banking requires segregated entity accounts, fiat and stablecoin invoicing, multi-currency treasury, payroll, role-based permissions, and AML across jurisdictions. A €1 consumer app does not address those needs.
The background: how banks are approaching crypto
From FDIC guidance to regulated bank partnerships
The FDIC’s 2022 guidance requires insured US banks to notify the agency before crypto activities. That guidance does not apply to an EU bank, but it shows global tension: regulators want bank crypto to be conditioned and supervised, while marketing often presents it as frictionless. The Fibank Bitpanda partnership shows how a European bank can sidestep tension by relying on a partner’s dedicated crypto licenses instead of using its own charter. NerdWallet’s crypto banking primer details these distinctions.
The BaaS model behind embedded crypto trading
Embedded crypto trading uses a banking-as-a-service model: a licensed fintech plugs its product into a bank’s digital environment. Visa’s overview describes it as “a financial institution partnering with a crypto platform to provide access to digital currencies alongside traditional banking products.” The bank avoids building a trading desk; the fintech gains distribution. Whether the revenue justifies integration cost and reputational risk remains unproven.
Custody, licenses, and the unanswered revenue question
Anchorage Digital represents institutional crypto custody for businesses and funds. FV Bank and Current represent consumer convenience and fee-driven trading. A Congressional Research Service report notes that these diverging approaches make a single regulatory framework for crypto banking elusive. The Fibank deal is consumer convenience; its economics depend on retail trading volume, not treasury services.
What business and DAO finance leads should do with this
Do not confuse a consumer trading feature with a business account
If your stack includes stablecoin payroll, cross-currency vendor payments, or DAO multisig treasury, a consumer trading widget is irrelevant. It cannot onboard a legal entity, issue corporate cards, manage role-based spending, or produce accounting-grade records. Treat the Fibank Bitpanda partnership as a retail revenue experiment.
Evaluate payroll, invoicing, cards, and multi-currency treasury separately
Do not shorten due diligence because a bank announced consumer crypto.
A Business Treasury Checklist for Evaluating Embedded Crypto Offers
- Segregated business crypto accounts, or personal-only?
- Invoicing in fiat and stablecoins synced to accounting?
- Role-based permissions and multi-signature controls?
- Custody model and liability for crypto custody for businesses?
- FX and cross-border wires in multiple currencies?
- Payroll and recurring tokenized compensation in fiat and crypto?
- Limits, fees, and settlement for large fiat-crypto conversions?
Use the partnership timeline as a benchmark
Early 2027 gives finance teams 12 to 18 months to watch execution, not commit. Watch for live go-live, corporate features, and follower banks. For stablecoin cross-border flows, see Citi and Coinbase’s checkout. DAOs should evaluate crypto treasury management as a first-class function.
What to watch next and open questions
Will other EU banks follow Fibank's embedded crypto route?
If activation is strong without regulatory friction, mid-tier banks in Central and Eastern Europe will likely replicate the BaaS crypto-onboarding model. A wave in 2027 would validate embedded crypto as the default European crypto banking strategy.
How Bitpanda’s custody and regulatory permissions hold up
Bitpanda Enterprise is regulated in Austria with multiple EU permissions. But when a bank app offers crypto and the custodian is not the bank, the consumer protection boundary is blurry. Outages, hacks, or disputes will test liability. See Standard Chartered’s RLUSD custody initiative.
Whether a business or DAO-specific version emerges
Neither Fibank nor Bitpanda has signaled a business or DAO banking module. The deal is consumer-only. That leaves room for crypto-native neo-banking for Web3 platforms that already provide corporate accounts, multi-currency wallets, invoicing, and DAO governance tools.
Key Questions About Crypto Banking and the Fibank-Bitpanda Deal
What is crypto banking?
Crypto banking generally means managing fiat and cryptocurrency through one account or interface. It ranges from a consumer “buy crypto” button to institutional custody, payments, and lending. Safety and licensing depend on the provider.
How does the Fibank-Bitpanda deal affect crypto banking?
The Fibank Bitpanda partnership shows a regional European bank embedding crypto trading without obtaining its own crypto license, by offloading custody and compliance to a fintech. It accelerates BaaS crypto distribution and may prompt followers. But it is a consumer retail feature, not business crypto banking.
Is crypto banking safe?
Safety depends on provider. Bank fiat deposits may be insured; crypto held by a third-party fintech is not covered by that insurance. Verify who holds crypto, which permissions apply, and whether client assets are segregated. NerdWallet details consumer distinctions; business complexity is higher.
Can businesses use Fibank’s crypto trading for payroll or invoicing?
No. The Fibank-Bitpanda offering is a consumer trading facility inside a personal banking app. It cannot onboard legal entities, issue corporate cards, process payroll, or handle fiat and stablecoin invoicing. Payroll and invoicing require multi-user access, accounting integrations, and treasury controls.
What does OneSafe offer for crypto banking?
OneSafe is a financial technology company providing a fiat and crypto platform for global businesses, startups, and DAOs. It offers global multi-currency accounts, corporate cards, FX, ACH and wire transfers, invoicing in fiat and stablecoins, and on-chain crypto payments. Crypto is held via Fireblocks custody, with customizable roles for DAO banking. Banking services are delivered through partner banks. OneSafe is not a bank.
How does OneSafe differ from traditional banks?
OneSafe is built for organizations operating natively across fiat and crypto. Unlike a bank adding a crypto toggle to a consumer app, OneSafe combines business crypto accounts, conversions, cross-border payments, and DAO wallet controls in one interface. It is a technology company, not a licensed bank; partner banks provide rails.
Who can open a crypto banking account for business?
OneSafe accounts are for startups, global enterprises, and DAOs managing fiat and crypto. Any properly registered legal entity can apply with formation documents and a government-issued ID. Onboarding typically completes within a week. Consumer accounts are not offered.
What is the difference between consumer crypto trading and business crypto banking?
Consumer trading lets an individual buy and sell crypto in a personal account. Business crypto banking requires entity-level accounts, multi-user permissions, invoicing and payment workflows, treasury tools, and corporate AML. A business cannot run payroll from a consumer app, and a DAO cannot enforce governance over a multisig through a retail bank app. The gap will widen as banks add consumer widgets.
Key Takeaways
- The Fibank Bitpanda partnership announced October 12, 2026 is consumer retail; live not before early 2027, not business crypto banking.
- The split between bank license and fintech custody means clarify who carries risk.
- Consumer trading apps do not cover business crypto accounts, payroll, invoicing, multi-currency treasury, or DAO banking.
- Other EU banks may follow, but benchmark execution, not announcements.
- For a unified fiat and crypto platform today, crypto-native neo-banking for Web3 platforms already serve business entities and DAOs.
Ready to open a business account that handles fiat and crypto together? Start your onboarding with OneSafe today.